|
|
By  David Craig, on November 26th, 2013 I have previously written about why we need to talk to our parents about their money. I imagine most readers thought either I was being excessively alarmist or else that as the people they knew over 60 were intelligent professionals, there’s no way they would allow themselves to be fleeced by financial services salespeople. If these were your reactions, you were wrong, very wrong.
Some facts:
Annuities – About 90% of annuities are mis-sold. This means annuitants are getting less money than they should every month for the rest of their lives. About 360,000 annuities are sold every year. So 324,000 a year (6,230 a week, 1,246 every working day) are mis-sold.
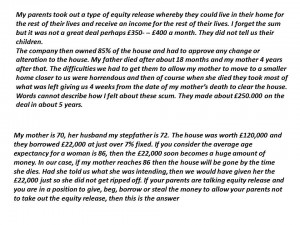
Equity Release – Equity Release is a fairly new product. When many people had final-salary pensions, there was little need for Equity Release. But as final-salary pensions have vanished and people are finding out how little there is in their retirement funds (due to high charges and poor investment performance) and how low annuity rates are, many are turning in desperation to Equity Release. We don’t know how widespread mis-selling is. But there’s no reason why it should be any less than with annuities (click on image to see clearly).
Dud investments – I wrote yesterday about how £60bn of savers’ money (usually older savers) has gone into worthless structured products sold by banks and another £75bn has gone into expensive unit trusts, 90% of which fail to even match overall stock-market performance due to their high charges.
There seem to be 3 main reasons why older savers are being constantly fleeced
1. They are part of Generation Trust – they come from a generation when you could trust you bank manager or pension adviser or financial adviser to look after your interests. So they fail to understand the levels of greed, dishonesty and corruption that are now rife in the sale of financial services
2. They’re too proud to admit problems – many older people are not used to talking to their children about their financial situation and are too proud to admit they are struggling. These makes them easy prey for people selling usurious equity release or dud investments
3. They’re vulnerable – Most of the country’s savings are owned by people approaching or already in retirement. Financial services insiders call them the “banana skin and grave brigade” because they have one foot on a financial banana skin (they know little to nothing about savings and investments) and one in the grave (so there’s no harm relieving them of their money before they go). Older people living increasingly isolated lives or on their own are particularly at risk as they’ll tend to be more accepting of a commission-based financial salesperson visiting them in their homes to flog them some supposedly ‘safe’ financial product. And people in retirement homes are also at risk as many retirement home managers have struck dirty little deals with financial sellers whereby they can come into the homes to sell their stuff and the manager(ess) gets a taxfree, cash in an envelope kickback from the seller.
The older generation are getting fleeced by the financial services industry. Don’t believe that just because someone had a successful active career that they’re immune. They’re not. In fact, they’re prime targets as they have confidence in their own judgement and so are more easily fooled.
You need to sit down with everyone you know who is over 60 and ask them “who is after your money?”. You have to find out which organisations – banks, investment companies (St James Place, Fisher Investments etc), equity release companies, boiler-room share sallers or whoever – have been soliciting them to get hold of their money. Then you have to explain why most of the stuff they are being sold is financial garbage designed to make the seller a lot richer than the buyer.
This is a difficult conversation to have. But if you do have it, you could save them from being thoroughly fleeced by today’s totally amoral financial services industry.
(Tomorrow – explosive stuff. A secret tape recording of two people called Wendy and Tony in the bedroom of a house owned by someone called Rupert. Don’t miss it!)
By David Craig, on November 24th, 2013 While those with mortgages may be partying over low interest rates, for those with savings, the Government’s attempts to lower the interest it pays on its ever-increasing debt (up from £700bn in 2010 to £1.4trn by 2015) are disastrous for anyone with savings.
You’ve probably read in the papers that savers are losing around £120bn a year in income from their savings because of low interest rates. But low interest rates have been even more damaging. Many people, who are risk averse and would never consider putting their money into stock-market investments, are being forced by low interest paid on bank accounts to move their money into supposed “investments” as they try to protect their money from inflation. (The Government claims inflation is only about 2.7% – probably it’s nearer 5%)
Since 2008/9, about £60bn of savers’ money has gone into investment products sold by banks and usually called something like “Guaranteed Growth Bonds” or “Guaranteed Investment Bonds”. I have previously explained why these are truly dreadful for savers but wonderful for the banks and City spivs who have created them www.snouts-in-the-trough.com/archives/7404
Up to 2008, we were putting about £10bn a year into unit trusts – since 2009 this has rocketed to £23bn a year, giving unit trust managers £75bn more than they would have got if interest rates had stayed at a normal level www.snouts-in-the-trough.com/archives/7414
So, that’s at least £135bn of our savings that have flowed out of things like 2- and 3-year fixed interest accounts and into risky stock-market schemes. Savers will be paying around 3% a year to the people who have sold these schemes and who manage their money. That’s an extra £4bn (£135bn x 3%). I don’t know how many people will benefit from this extra £4bn a year – let’s say it’s 5,000 at most (I suspect it’s fewer). Then splitting this £4bn amongst these 5,000 financial services insiders, that’s an extra £800,000 a year each – all due to desperate savers moving money from relatively safe bank accounts into financial products developed by City spivs to make themselves rich at ordinary savers’ expense. Low interest rates have certainly been rather good for the Tories’ friends in the City.
Equity Release – A couple of days ago I wrote a piece warning of the dangers of Equity Release www.snouts-in-the-trough.com/archives/7529 . Here’s another reader’s story:
“Dear David. Been away so I have only just read your article about equity release. My parents took out a type of equity release whereby they could live in their home for the rest of their lives and receive an income for the rest of their lives. I forget the sum but it was not a great deal perhaps £350- – £400 a month. They did not tell us their children. The company then owned 85% of the house and had to approve any change or alteration to the house. My father died after about 18 months and my mother 4 years after that. The difficulties we had to get them to allow my mother to move to a smaller home closer to us were horrendous and then of course when she died they took most of what was left giving us 4 weeks from the date of my mother’s death to clear the house. Words cannot describe how I felt about these scum. They made about £250.000 on the deal in about 5 years.
It was painful to lose the money I must admit, but much more painful was trying to get them to allow my mother to move to be closer to us in her last days. They are inhuman”
By David Craig, on November 24th, 2013 I know some readers will be upset by my descent into “smut”. But I’ve written 1,242 posts on this website and I think only about 5 or 6 (less than 0.5%) have mentioned s*x.
Any way there’s good news for those of us who find s*x tourism rather questionable. Many girls don’t want to do it any more.
Here in the Land of Sm*les, it has long been the tradition in poor families that the daughters leave school early to work and provide for their families while the sons stayed in school to get an education and then hopefully a job. Given that most girls had no qualifications, many had little choice but to move into the s*x industry to live up to their family obligations.
However, things are slowly changing – for the better. With economic growth, there are fewer very poor families, so more girls are staying in school for longer and then are getting proper jobs in factories and offices. This is causing a huge problem for gogo bar owners – they’re finding it increasingly difficult to get the staff they need to pull in the punters.
I was talking to one manager a couple of days ago. “It’s a disaster”, he explained, “girls don’t want to dance in bars any more. We’ve been forced to increase wages, but still we can’t get enough good-looking ones”. He went on to lament the fact that even when he could get girls, they wanted to dance in their bikinis and wouldn’t even take their tops off to show their breasts. As for dancing naked, which used to be the norm, very few would agree to this. Even worse for him, he needed girls to do what he called “the naughty stuff” – pushing various objects including bananas and rubber penises into themselves and letting men do all sorts of things to them – it was almost impossible to find any girls who would do that nowadays.
The traditional image most male s*x tourists have of the Land of Sm*les is probably like this:

But, in fact, many (maybe even most) of the girls still in the industry are long since past the first flush of youth and some are even matronly rather than nymphettish. An awful lot seem to have had at least one, and often several, children which doesn’t do wonders for your body and makes dancing naked for 7 to 8 hours a day not a viable proposition – hence they prefer to keep as many of their clothes on as possible.
However, the gogo bar owners are not giving up. In a couple of years, the main Asian countries are starting their own Common Market – a free trade and free movement area (without the political and bureaucratic monstrosity that is ruining Europe). This will mean that girls from poorer countries like Myanmar, Laos and Cambodia should be able to come and work in the Land of Sm*les – providing lots of fresh young meat for the gogo bar owners.
As for European female sex tourists, the lack of economic progress in Africa and the Carribbean means they’ll still be able to enjoy the pleasures they can’t get at home in dreary old Britain

By David Craig, on November 23rd, 2013 I don’t know if you’ve ever watched Formula 1 (F1) racing. I tried a couple of times then gave up at the sheer boredom. Apparently years ago the cars used to actually race each other and sometimes even overtake. But now the race is like a high-speed procession. Half of all races are won by the car that starts in pole position. Almost all races are won by the car that starts in pole, second or third position. So you pretty much know who is going to win the race even before it has started.
The commentators try to inject some excitement into this procession. And when the leading car goes in for a pit stop, the order does change for a few minutes. But then the other cars go in for their pit stops and the original procession resumes. So how can you make squillions from a product that is only slightly more exciting than watching paint dry? That’s the genius of Bernie Ecclestone.
What he has done, as far as I can see, is go to some developing countries. These are usually countries that have contributed little or nothing to human advancement in science, technology or the arts. Countries that wouldn’t recognise a Nobel Prize if it hit them in the face. And Ecclestone has, I think, sold these countries on the story that if they give him piles of cash, he’ll hold a F1 Grand Prix in their country and that will make their country seem modern and developed.
Thus we got the Malaysian Grand Prix in 1999. In 2004 both China and that great world power Bahrain handed over their cash to join the Grand Prix club. In 2005 that beacon of development and modernity Turkey held its first race. In 2009, that leading international powerhouse and centre of scientific advancement Abu Dhabi signed up. Then in 2010 there was Korea and in 2011 India – one of the most corrupt unequal countries outside of Africa.
So where will F1 go next? What about Africa? There’s oil-rich Nigeria. They have loads of money even though 90% of the population live in poverty. Or Equatorial Guinea – again gazzillions of money even though 98% of the population live in abject poverty. Yup, Africa seems to provide just what F1 is looking for – countries with heaps of money and nothing to show for that money apart from corruption. backwardness and oppression.
Although, perhaps I shouldn’t criticise the (in my opinion pointless) F1. Over 500 million people apparently watch it. That’s rather more (unfortunately) than read my website or books.
If I may, I’d like to publish 2 comments readers sent me following my blog yesterday warning about the dangers of Equity Release loans:
“In certain circumstances equity release is a great idea. Take your asset rich cash poor couple for example. If they don’t want to trade down and have no children what’s wrong with taking a bit of equity out?”
“Another gem. Why is it, that when we become old we are sitting ducks for all and sundry? Ten years ago my friends were short on cash, and they asked my opinion about Equity Release. I told them to keep well away, and gave them an example of interest growth. They were astounded. Their daughter came up with the solution. She increased her mortgage, and saved herself a load of grief.”
By David Craig, on November 22nd, 2013 Apologies if today’s post is not directly relevant to you in your financial situation at your time of life. But we all know people who are either about to retire or who are retired. What we probably don’t know – because people of that generation are often reluctant to talk about money – is that these people are being aggressively, even viciously targeted by Equity Release companies.
As part of my research for my next book, I went to a supposedly free seminar recently all about ensuring “a financially secure retirement“. In fact it was just a hard sell session for Equity Release. What was deeply worrying was the queue of people at the end all signing up to arrange for the salesman to visit them in their homes to discuss them taking an Equity Release loan.
What is Equity Release? Many older people are what financials services companies call “asset rich, cash poor“. They have houses (assets) which may be worth quite a lot of money. But because their pensions have performed so badly and because annuity rates and interest rates are so low, these people may be struggling to find enough money to have a comfortable retirement. They have a tough choice – sell their homes to generate some cash or continue to struggle. This makes them perfect targets for smooth-tongued, unscrupulous salespeople proposing that these people can stay in their homes by taking out a loan against their homes – a loan that doesn’t have to be repaid till they either move into a nursing home or die. Sounds pretty good!
So what’s wrong with Equity Release? The interest rates. Interest rates on Equity Release are only a couple of percentage points above a mortgage. So they sound like a good deal. But over 15 to 20 years, this small difference in interest rate can add up to a huge amount of money.
Just one example – if someone takes out an Equity Release loan of £53,000 (that’s the average size) when they’re 66, they’ll owe about £200,000 by the time they’re 86. In comparison, if their children had added £53,000 to their mortgage (to help their parents out), then they would only have had to repay about £95,000 over 20 years. So the family (parents and children) would be £105,000 better off (£5,000 a year) if that £53,000 loan had been added to the children’s mortgage rather than being taken out as an expensive Equity Release loan.
Let me give you a quote from a family which found out their parents had been conned into taking out an Equity Release loan:
My mother is 70, her husband my stepfather is 72. The house was worth £120,000 and they borrowed £22,000 at just over 7% fixed. If you consider the average age expectancy for a woman is 86, then the £22,000 soon becomes a huge amount of money. In our case, if my mother reaches 86 then the house will be gone by the time she dies. Had she told us what she was intending, then we would have given her the £22,000 just so she did not get ripped off. If your parents are talking equity release and you are in a position to give, beg, borrow or steal the money to allow your parents not to take out the equity release, then this is the answer.
Hopefully that’s pretty clear.
Each month or so I get a booklet from an Equity Release company – I think it’s called Retirement Solutions – pushing Equity Release and full of stories of happy, healthy pensioners who have been able to take the holiday of a lifetime, visit their grandchildren in Australia, Canada or wherever, finish a home extension etc etc thanks to the generosity of the Equity Release business. Just wait till payback time comes and see how happy and smiling they are when they find out that a small, supposedly manageable loan has mushroomed into a mountain of debt that will leave their heirs penniless.
Equity Release may work for a few people – those who intend to leave little to nothing for their children or relatives after their deaths and who don’t plan to save anything for care home fees. But for most people, it’s an expensive disaster. So, please please talk to any retired people you know, ask if they’re being pestered by Equity Release salespeople and warn them that seemingly small Equity Release loans can wreck their family’s financial future (while ensuring a comfortable living for the Equity Release seller).
(If any readers or people readers know have taken out Equity Release, I’d be interested to know if they’re satisfied or whether they’ve realised that they’ve made a serious financial error. I’ll publish any answers)
By David Craig, on November 21st, 2013  I’m rushed for time today and so thought about doing a piece on how obese sex tourists (often weighing 200kg or more as in the pictures above) do boom boom with girls in the Land of Sm*iles often weighing around 45kg.
But following complaints from readers about my “descent into smut” when I did a piece on Gogo Bar girls, I’ll spare you the grisly anatomical details.
Instead, I’ll write about the Pattaya Flying Club.
Just up the road from the beach resort where I’m staying, is the world famous Pattaya. Expats talk about something they call the “Pattaya Flying Club”. These are the Falang (white foreigners) who go to meet their Maker after jumping (or being pushed) off a balcony – preferably sixth floor or above to get the best results. There seem to be 4 main types of members.
1. Party party, whoops I’m broke – some men come here and are completely intoxicated by the sun and the party atmosphere. They spend their days (and nights) in bars surrounded by admiring locals who laugh at all their jokes and make them feel important and appreciated for the first time in their sad, loveless lives. Often they overstay their visas enjoying the wonderful food, cheap alcohol and unlimited quantities of s*x. But one day they wake up from their hangover, in bed with several girls (or boys depending on their preference) broke and in trouble. Ashamed to go back and face their families and friends, they walk out onto their balcony and wheeeeee – they join the Pattaya Flying Club.
2. I run a successful bar in Th**land – Many Falang come here during high season, see the bars teeming with tourists and think – “hey, this is the good life”. So they buy a bar, spend their life savings doing it up and wait for the money to come pouring in as they spend their days eating, drinking and having s*x. But then the rainy season arrives, there are no tourists and they watch day after day as their money pours out. Finally, bankrupt, unable to find a sucker to buy their pathetic little bar from them, they too are ashamed to go back to their families and friends to admit their failure and so out onto the balcony they go and wheeeee – members of the Pattaya Flying Club
3. But she (he) said she loved me – Then we have those who have settled down with a local girl (or buy depending on their tastes), have lavished money on their partner and then find out their partner is seeing other men. Often this is hardly surprising when the Falang is 50 or 60 years old and their girlfriend (or boyfriend) is about 20 and wants some fun in their lives. In despair, some of these men head out to the balcony and join the Club
4. I was happily married – Quite a few Falang are so entranced with the lifestyle in the Land of Sm*les that they marry a local girl (perhaps not knowing that she is already married to a local man). Foreigners cannot buy land or houses here (they can buy some condos) and so often have to put their properties in the name of their local partner. Once they are firmly married and the wife has full title to their property and their assets should they happen to die, some of these Falang (even though they may only own a one-story house) manage to find themselves in a condo (6th floor and above) where they apparently decide (usually with a little help from their wife’s local husband or friends or family) to also take a lifetime membership of the Pattaya Flying Club. Naturally the police here are most understanding and class all such cases as “suicide”.
I have loads of pictures of members of the Pattaya Fling Club, but will spare you these in the interests of decency.
Whoops – I’ve just realised, my condo is on the sixth floor. If I ever join the Pattaya Flying Club, please note this is not out of choice.
By David Craig, on November 20th, 2013 Yesterday the Torygraph’s chief political correspondent was wetting his expensive designer knickers over the fact that the laughable Ed Miliband looks set to win the 2015 General Election. “How was it possible,” moaned the journalist, “that millions of people could vote for a party which had wrecked the British economy and been totally discredited?”
In the comments section, hundreds of Torygraph readers took the time to explain why Cameron couldn’t win the last election and certainly won’t win the next one. One reader made some interesting philosophical comments about why Western democracies which bribed voters with their own money will always be bound to fail and go bankrupt:
Alexander Fraser Tytler (1747-1813), ‘A democracy cannot exist as a permanent form of government. It can only exist until voters discover that they can vote themselves largesse from the Public Treasury. From that moment on, the majority always votes for the candidates promising the most benefits from the Public Treasury with the result that a democracy always collapses over loose fiscal policy, always followed by dictatorship’.
Alexis de Tocqueville observed: ‘The American Republic will endure until the day Congress discovers that it can bribe the public with the public’s money.’
The above explains why, it is the people who are ‘rational’ by voting for those who offer them the most. The opposition (Labour) will offer the most and voters will be bribed by their own greed, with their own money, which will be paid back later, by less and less services, more and more confiscations (taxes), and by poorer standards of living for their own children whom they gladly sold for short term gain
But most vented their outrage at how little Cameron had achieved and how he lost the opportunity to save Britain from its own self-destruction:
“It’s really quite simple, Cameron has absolutely nothing in common with voters outside of London. He had a golden opportunity to finish Labour once and for all. Immigration, Europe and Law and Order have been the biggest issues for the electorate over the last 30 years and in opposition he said the right things( cast iron guarantee anybody) but he has failed miserably. He needs to kick out all illegals, say no to Europe on the entry of the Romanians and Turks and start and repatriate powers and be tough on crime…in other words the decisions that take guts and bravery, forcing through gay marriage, committing to foreign aid and a referendum on Scotland was weak and pathetic.
How one man given such a wonderful opportunity to put things right has totally f*cked up and made labour electable again beggars belief….but then again do any of these millionaire political class career politicians really care about Britain?”
Having read through quite a few comments, I’ll try to summaries Cameron’s “achievements”

By David Craig, on November 19th, 2013 As we approach the May 2014 EU elections, we will be drowned with misinformation from the ConLibLab Party and their cheerleaders in the media.
Cameron will blether on about his wonderful “renegotiation” and how he’ll get a “deal that’s good for Britain”. This is rubbish. The EU does not negotiate. It does not respect agreements and it does not respect democracy. It is only interested in increasing its own power. When Blair gave away a huge chunk of Britain’s rebate in return for supposed changes to the Common Agricultural Policy, the EU took our money then refused to live up to its side of the deal. And on the few occasions a few countries have been allowed to vote on EU issues, if the vote doesn’t go the way the EU wants, it just makes people vote again. And if that doesn’t give the right answer, it just does what it wants anyway.

Clegg will witter on about “3 million British jobs will be lost if we leave the EU”. Like most of what schoolboy Clegg says, this is a lie. If we left the EU, European countries would continue to trade with us. Firstly, they cannot impose special tariffs and import restrictions on British goods as that would be breaking WTO rules. Secondly, EU countries sell much more to us than we sell to them. If the EU bureaucrats tried to punish Britain by starting a trade war, millions of jobs would be lost – mainly in EU countries. So, within 24 hours of leaving the EU, we would have trade deals in place with most countries and the Brussels bureaucrats would be left fuming impotently in their rage that a country had the temerity to call their bluff and leave their corrupt, wasteful great EU superstate.
Miliband will probably claim that it’s better for Britain to be “in Europe influencing EU policy”. This is also rubbish. Britain has just one vote among 28 (soon to be 30 or more) countries. The countries taking more out of the EU than they put in massively outnumber the countries that contribute more than they receive. Therefore there will always be a majority for more spending, more central control, more bureaucracy, less democracy. Britain is powerless to stop this.
We have a very clear choice in May 2014:
Do we want Britain to remain an independent country with control of its own borders, police, military, trade, agriculture, fisheries, social security, healthcare and laws?
Or do we agree to becoming a minor region of a 500-million-people EU superstate where we will serve two purposes for our unelected EU masters. We will be a cash cow to be mercilessly milked to pay for the venal, wasteful Brussels bureaucracy and the overspending, corrupt, failed Club Med and Eastern European countries. And we will be a dumping ground for all the benefits-scrounging garbage from across the EU who see they can have an easy life in the UK at British taxpayers’ expense.
We have already given control of our agriculture, fisheries, trade and borders to the EU – with catastrophic consequences. And a country that no longer controls its own borders is not a country any more.
So, please see through the smoke and mirrors that will come from our self-serving establishment. Our choice is clear – do we want Britain as an independent country, or Britain as a administrative region of a huge corrupt, wasteful superstate ruled by unelected Kommissars? That’s what we we’ll be voting on in May 2014. Please make the right decision. And please influence those you know to make the right decision too.
By David Craig, on November 18th, 2013 I’ve written before about the many benefits Britain’s 300,000-strong Somali community have brought to our country – religious intolerance, FGM, oppression of women, terrorism and murder and a massive drain on our country’s resources. With only about 35% of Somali men and less than 10% of Somali women in work, I believe that Britain’s Somalis are costing us over £6bn a year in housing, education, healthcare and benefits. In fact, Britain’s Somalis make so much money in benefits that they can easily afford to send around £500m a year of our money back to their extended families in the blighted hell-hole Somalia.
But this cost of £6bn a year doesn’t take account of the social disruption caused by Britain’s Somalis – the underachievement of Somali children in our schools which is disrupting the education of children who actually want to learn something, the blocking of our healthcare system so that British people who have worked and paid tax all their lives cannot get medical care, the vast amount of social housing that has been given to Somalis leaving British workers in expensive rented accommodation, the extraordinarily high level of criminality among Somali youth which is tying up police and court resources and the fact that to thank us for our generosity to them, Britain’s Somalis hate us and have been the most active group launching terrorist attacks against our country.
But the problems that Britain’s wonderful Somali community are causing us, may soon seem like small beer compared to the joys that lie in store for us when the Roma invasion really gets going. We already have (according to Government statistics) over 200,000 Roma in Britain. So, the real figure is probably double that. The Government won’t tell us what the unemployment rate amongst the Roma is. But I would suspect that less than 10% of Roma men and less than 5% of Roma women actually do any legal paid work. We can reasonably reliably assume that the Roma are already costing us as much as our parasitical Somalis – so about £6bn a year. At least another 500,000 (and possibly more) Roma will to flood into Britain once they gain full rights to these benefits after 1 January 2014
- Attendance Allowance
- Child Benefit
- Council Tax Benefit
- Disability Living Allowance
- Guardian’s Allowance
- Housing Benefit
- Income Support
- Income-based Jobseeker’s Allowance
- Industrial Injuries Disablement Benefit
- Carer’s allowance
- Reduced Earnings Allowance
- Severe Disablement Allowance
- Statutory Sick Pay
- State Pension
Then we can expect the direct cost of Roma to hit say £12bn a year.

As one Roma village leader said, “The only thing that will be left here is the donkey”.
Then there is the social disruption – anti-social behaviour, disruption to the NHS, disruption with our social services, disruption in our schools (when the Roma children can be bothered to turn up), high levels of criminality (especially burglary), destruction of neighbourhoods and so on. The situation is already so bad in Sheffield that David Blunkett has predicted race riots.
And there’s absolutely nothing we can do about this impending disaster for our country because it’s Portuguese ex-communist Barosso who decides who can come to Britain, not the British Government. I think we should give up the Armistice Day ceremonies – after all, today’s greedy, self-serving, spineless politicians have given away the freedoms for which so many hundreds of thousands fought and died
By David Craig, on November 17th, 2013 Following various brushes with Elizabeth Filkin, the (I believe) honest, dedicated Ms Filkin was forced from her job to be replaced by a much more malleable establishment time-server. Meanwhile the “Right Honourable” Keith Vaz who is (I believe) a lying, greedy, self-serving, expenses-fiddling, home-flipping scumbag was allowed to continue leeching millions in taxpayers’ money for many more fruitful (for him) years.

Suspension from House of Commons
In 2002, Vaz was suspended from the House of Commonsfor one month after a Committee on Standards and Privileges inquiry found that he had made false allegations against Eileen Eggington, a former policewoman. The committee concluded that “Mr Vaz recklessly made a damaging allegation against Miss Eggington to the Commissioner, which was not true, and which could have intimidated Miss Eggington or undermined her credibility”.
Nadhmi Auchie
In 2001, it was revealed that Vaz had assisted Anglo-Iraqi billionaire Nadhmi Auchi in his attempts to avoid extradition to France. Opposition MPs called for an investigation into what one dubbed “Hinduja Mark II” Anglo-Iraqi billionaire Nadhmi Auchi was wanted for questioning by French police for his alleged role in the notorious Elf Aquitaine fraud scandal which led to the arrest of a former French Foreign Minister. The warrant issued by French authorities in July 2000 Auchi of “complicity in the misuse of company assets and receiving embezzled company assets“. It also covered Auchi’s associate Nasir Abid and stated that, if found guilty of the alleged offences, both men could face 109 years in jail.
Vaz was a director of the British arm of Auchi’s corporation, General Mediterranean Holdings,
Home Affairs Select Committee
Vaz was elected Chair of the Home Affairs Select Committee, replacing John Denham, on 26 July 2007. He was unusually nominated to the Committee by the Government, rather than by the quasi-independent Committee of Selection which, under the Standing Orders of the House, nominates members to select committees. The Leader of the House argued that this was because there was not sufficient time to go through the usual procedure before the impending summer recess. The Chairman of the Committee of Selection told the House that the Committee had been ready to meet earlier that week, but had been advised by the Government that there was no business for it to transact. As Chair of this important committee, My Vaz regularly lectures all and sundry about the importance of probity in public life. You couldn’t make it up!
Parliamentary expenses
In terms of expenses, Keith Vaz is usually in the top 10% of MPs by the amounts he claims and after the Telegraph revlations, Vaz was forced to make several repayments

BCCI “fraud” by Deloittes and Keith Vaz’s “involvement”
I briefly came across the charming Mr Vaz in 2005. After my book RIP-OFF was published, I was contacted by someone claiming to be a senior forensic accountant at Deloittes. His story was that working on a team of hundreds managed by “Sir” Fred Goodwin, he had helped Deloittes defraud the creditors of the BCCI (Bank of Credit and Commerce International) of possibly up to £100m. The BCCI was based in both Luxembourg and London. When the Luxembourg authorities saw what Deloittes were up to, they took legal action against Deloittes and Deloittes settled out of court handing back many millions. At the same time, two British MPs, one of whom I believe was Keith Vaz, enjoyed a luxury, all-expenses-paid trip out to the Middle East to see what Deloittes were up to. Although the Luxembourg authorities apparently caught Goodwin and Deloittes with their hands firmly in the till, these two British MPs apparently saw nothing wrong at all and no action was taken against Deloittes in Britain.
You have to remember that the BCCI preyed mainly on British Asian businesspeople, many of whom were Mr Vaz’s constituents. I contacted Vaz’s office and explained that I had access to documents proving what Deloittes had been up to. In spite of several calls to his office, he never made any attempt to get back to me to look at the evidence that Deloittes had allegedly defrauded many of his constituents and supporters.
Yup, perhaps Keith Vaz deserves our much-coveted Trougher of the Year trophy
|
|