|
|
By  David Craig, on December 1st, 2013 I’m not going to answer this question in a 600-word blog – but it’s something that puzzles me
It can’t be that difficult to run a country properly. After all, we know that tight central control, imprisoning opponents and widespread kleptomania by the ruling elites isn’t a recipe for success. Whereas promoting development, opening the country to investment and tourism and encouraging education are the right sort of things to do. So, why are so many countries such utter hellholes?
Let’s start with Egypt. Mohamed Morsi became the first democratically elected president in the country’s history. He took power with a huge wave of public support and the US and EU offering billions in aid. So, what did he do? Encourage investment and tourism? No. Try to improve the lives of the majority of his people? No. Instead he perverted the constitution granting himself unlimited power to “protect the nation”, encouraged religious intolerance, persecuted minorities and put his Muslim Brotherhood cronies into positions where they could enrich themselves while condemning most of Egypt’s 81 million population to grinding poverty. What a disaster! What a lost opportunity! And this guy got his PhD in the US and even taught there for a while. So he should know better. I imagine the result of this idiot’s short-sightedness will be 10 years or more of a low-level civil war and maybe 100,000 dead as in Algeria.
Most of Africa is a hopeless basket case, where almost all the leaders think like the mad Robert Mugabe and act like the ludicrous (but now rich) Jacob Zuma. I doubt there’s an African leader with less than $1bn stashed away in offshore bank accounts. I imagine the average is somewhere between $10bn to $20BN. Why do they need to steal so much money? How much can they spend, eat, drink and screw? They could run their countries properly and still enrich themselves. But none of them seem to care. They just loot all they can and to hell with the poor sods they rule.

Here in Th**land, there’s a similar collapse of sensible government. Th**land has been a great Asian success story. It has a massive tourist industry and is one of the largest car-makers in the world. But now there’s competition from Cambodia, Vietnam and even Myanmar. So what does the current leader do? Strive to make her country a stable attractive place for foreign investment? Nope. Instead she risks provoking total political breakdown and a military coup by trying to pass an amnesty that would allow her brother – a former PM accused of looting billions while he was in power – to return to the country so he can carry on looting. The stock market and currency are in freefall and commentators are talking about the country committing “economic suicide”. Why? How much more money does the guy need to steal? Why such poor government?
Then there’s Britain under idiots Blair, Brown and Balls. While Blair was gallivanting around the world setting up good contacts to enrich himself after he left office, Brown and Balls wrecked our economy. They inherited a wonderful situation – a growing economy with tax revenue exceeding spending. So, as they had committed to sticking to the previous Tory government’s spending plans for the first 2 years in office, they were able to pay down our national debt by almost £20bn a year. With rising taxes, they could have massively increased public spending wasting a trillion or so on hiring an extra million bureaucrats and hugely increasing public-sector salaries. But no, they wanted to waste even more. So they let spending outstrip rising tax revenues (apologies for the quality of the images, but for some reason WordPress is acting up).

And as Mr Micawber should always remind us “Annual income £400bn, annual expenditure £390bn, result happiness. Annual income £400bn, annual expenditure £410bn, result misery”
So, that’s what I really don’t understand – why are so many countries (including our own) so badly governed?
By David Craig, on November 30th, 2013 My brother was smart enough to emigrate to Australia in his 30s and it may be interesting to compare our prospects. We both worked as consultants – though being cleverer than me, he was in IT systems whereas I could only manage general organisational effectiveness. But I imagine we’ve earned roughly similar amounts. So how can he retire in comfort whereas I’ll die in poverty?
1. Pensions – for a start charges on Australian pension funds are only about a third of what we pay in Rip-Off Britain. Moreover, as the Australian Government isn’t bankrupt, it isn’t holding interest rates artificially low. So, annuity rates in Australia are about 30% higher than in Bankrupt Britain. All this means that an Australian saving the same amount each year as a Brit would end up with over twice the pension income
2. Proper government – Australia has flirted with Labour governments. Most recently with the appalling Welsh-born socialist Julia Gillard. She did a “Gordon Brown”. Realising she was not electable, she hid behind a party leader that was electable and then when her party won an election, she moved out of the shadows to grab the PM job in spite of never being elected. But like Brown, her government dissolved into utter chaos. Luckily for Australia, a conservative government replaced the overspending Labour idiots. But in Britain, our overspending Labour idiots have been replaced by equally overspending Coalition idiots and with our national debt shooting up over 2010-2015 from £700bn to £1.4trn we are rapidly going bust.
3. Global Warming scam – while Dave “Hug a Husky” Cameron continues to inflict pointless green taxes which are pushing up energy costs and destroying British jobs, the Australian government has realised that the whole Global Warming thing was a complete scam and is getting rid of the job-destroying green taxes so enthusiastically introduced by Welsh-born socialist Gillard
4. Immigration control – Australia is lucky that it is an island and can control its borders. Moreover, as Australia is an independent country, it can decide who it allows in and who to reject. Britain, on the other hand…….whoops, Britain’s an island too. So we could theoretically control our borders just like Australia does. Oh no, I forgot. Our europhiliac politicians have handed control of our borders to a corrupt communist from paedophile paradise Portugal. So, it’s Barroso who decides who can come to Britain, not our own government.
5. Public services – As Australia is not drowning under a flood of at least 7 million mostly low-skilled, low-earning, rapidly-reproducing immigrants, Australia can afford to provide decent schools, proper healthcare, effective policing, decent housing and all the other benefits of a modern developed society. But as Britain is overwhelmed by often benefits-scrounging garbage who see Benefits Britain as a soft touch, our schools, NHS, policing, prisons, social housing, social security and other services are all collapsing and people who have worked and paid taxes all their lives find that they have become second-class citizens in their own country as immigrants seem to be given priority over the indigenous population for services and benefits
6. Different deaths – my brother will probably die peacefully in his bed at a ripe old age after a long and worry-free life. I will probably be one of the 34,000 people a year who die unnecessarily from an infection or poor care in Sir David Nicholson’s filthy slaughterhouse hospitals. Meanwhile the doctors and nurses who probably speak little English and who are paid from my taxes haven’t got time to look after me properly as they’re busy providing care to extended families of 15-20 Roma gypsies, just arrived in Britain, who have never contributed anything to this country and will only contribute dirt, crime and misery to everyone with whom they come into contact, who are all demanding NHS care as their human right as EU citizens
7. First World versus Third World – Not being bankrupt, swamped by immigration and committing economic suicide with job-destroying green taxes, Australia can continue to develop and offer its citizens an ever better life – better schooling, better healthcare, better housing, better public transport etc. Meanwhile Britain is rapidly turning from a civilised First World developed country into a corrupt, overcrowded,, garbage strewn, Third World backwater that is failing to provide even the most basic services for its citizens.
In 50 years, historians will look at rotten, chaotic, overcrowded, impoverished, declining, multicultural, Third World Britain and wonder how any country could have thrown away its future so carelessly.
(Oh and in case you’re thinking “if he believes Australia is so wonderful, why doesn’t he just bugger off there and leave us in peace?” – I would if I could. But following the collapse in the value of the pound against the Australian dollar, Australia wouldn’t let me in. After all, the Australians don’t want too much impoverished Third World trash, like me, washing up on their shores)
By David Craig, on November 28th, 2013 You probably know that most airlines have nicknames based on their customers’ experiences. Some of the best known are probably:
BA – Bloody Awful or Best Avoid: Alitalia – Always Late In Take-off Always Late In Arrival or Aircraft Late Into Tokyo All Luggage In Amsterdam: Sabena – Such A Bad Experience Never Again: PIA – Please Inform Allah or Perhaps I’ll Arrive: Quantas – Queers and Transvestites Serving As Stewardesses (from the days when Quantas only had male staff) or Quick And Nasty Transportation Australian Style: Delta – Don’t Expect Luggage To Arrive: TWA – Touch Wood Again or That Was Awful: TAP – Take Another Plane: Taca – Take Another Carrier Amigo: LOT – Luggage On Tarmac: TAT – Take A Train: People Express – People Compress: Ryanair – Conair or Eire O’Flot etc.
So I’d like to propose a new nickname for Emirates Airways – Excrement Airways. I’ve never travelled with Excrement Airways, though I did once go with one of the Arab airlines and that put me off them for life. After all, you should be paid to sit for 15 hours in a noisy, foul-smelling sewer, you shouldn’t have to pay for it.
However, my wife has just flown with Excrement Airways. The first leg from London to the middle of some desert wasn’t too bad. The passengers behaved as if they were in an Arab souk, but at least most of them had seen a Western toilet and knew more or less (there were some exceptions) how to use it. However, the leg from the middle of some desert to Bangkok was apparently horrible.
Unfortunately most of the passengers were baffled by the toilet arrangements. Some tried standing and then crouching on the seat and, as their aim wasn’t 100% on target, left their deposits a bit all over the place. Others had never used toilet paper and so wiped their soiled fingers on the toilet walls. And many who did understand the purpose of toilet paper threw it on the floor after use as there wasn’t a bin to put it in. As my wife later said, “you wouldn’t have liked it”.
Now, of course, you may have flown with Excrement Airways and had a wonderful flight with all the passengers on your flight fully toilet trained. But it seems that along with the safety announcements, Excrement Airways should also show a short film explaining (or get the cabin crew to demonstrate?) how to use a Western toilet. Until they do that, I think I’d rather pay a couple of hundred quid more to travel with an airline whose passengers understand the basics of defecating in an aircraft loo (Click on picture to see more clearly).

(Btw – Since Emirates took over the Arsenal stadium, I wonder if they’ve replaced all those clean Western toilets with those wonderful holes in the floor where you have to run fast when flushing (if they can be flushed) so you don’t get your feet wet or worse).
By David Craig, on November 27th, 2013 Hopefully you all know the speech given by Oliver Cromwell on 20 April 1653 when he dissolved Parliament:
It is high time for me to put an end to your sitting in this place,which you have dishonored by your contempt of all virtue, and defiled by your practice of every vice; ye are a factious crew, and enemies to all good government; ye are a pack of mercenary wretches, and would like Esau sell your country for a mess of pottage, and like Judas betray your God for a few pieces of money.
Is there a single virtue now remaining amongst you? Is there one vice you do not possess? Ye have no more religion than my horse; gold is your God; which of you have not barter’d your conscience for bribes? Is there a man amongst you that has the least care for the good of the Commonwealth?
Ye sordid prostitutes have you not defil’d this sacred place, and turn’d the Lord’s temple into a den of thieves, by your immoral principles and wicked practices? Ye are grown intolerably odious to the whole nation; you were deputed here by the people to get grievances redress’d, are yourselves gone!
So! Take away that shining bauble there, and lock up the doors. In the name of God, go!
It’s difficult to find anything in this 360-year-old speech that is not as relevant today as its was when first made.
What seems to happen in Britain is that after each cataclysmic war, we get MPs who either because of genuine morality or to preserve their own power actually enact legislation that benefits ordinary people. After the First World War, unemployment benefit was introduced. And after the Second World War, the NHS was set up. But as memories of war fade, a new generation of politicians take over. These new politicians are only interested in using Parliament as a means of enriching themselves and furthering their own lousy careers. To hell with the stupid people who voted for them.
Although I have spent the last 8 years writing books in defence of freedom and democracy and fairness, I believe our current MPs are so greedy, arrogant, self-serving, corrupted and incompetent that I wouldn’t be overly upset if a new Cromwell rose up and dissolved our Parliament of Whores.
Perhaps Britain’s generals, instead of looking for well-paid jobs working for arms companies could realise that our country is being sold out to the corrupt, wasteful, undemocratic EU. Perhaps they could dissolve Parliament, indict our political leaders for treason and pass some laws that benefited Britain – unilaterally withdraw from the EU, impose proper border controls, give no benefits to immigrants till they have worked for 10 years, throw out all illegal and unemployed immigrants, set a maximum public-sector salary of £89,000, set a maximum public-sector pension of £30,000 (if bureaucrats want more then they can save in overcharging underperforming pension funds like the rest of us), get rid of a couple of hundred pointless quangos, declare all power, water and airport companies “strategic national assets” that can only be owned by companies based fully for tax purposes in the UK, start prosecuting a few hundred of our corrupt banksters, deny any benefits or any social housing to anyone under 25 (let their parents look after and house them), abolish child credits while pushing up the rate for paying income tax to £12,000 (Britain is overcrowded – if people want children let them pay for them themselves) and other such measures to change Britain’s benefits culture. And they could organise new elections with just 200 seats in the Commons and 100 in the Lords.
Of course, this will never happen. But a military coup wouldn’t be the worst thing that could happen to our country. Handing over total control to the horrific socialist paradise of the EU would be worse.
We don’t have a new Cromwell – that’s why we all have to vote for UKIP.
By David Craig, on November 26th, 2013  As vicious and hurtful rumours spread of a love triangle including Rupert Murdoch, his delectable Asian wife Wendy and our very own Tony Blair, I’ve been handed the transcript of a recording made by the Iranian Intelligence Service (Iranian Intelligence? Sounds like an oxymoron. Ed.)
I don’t know who the speakers are, but let’s call the woman Wendy and the man Tony.
Wendy: Oh Tony, oh Tony , ooohh, aaaah, ooooh, aaaaaahhh, ayaieeeyaaaoooeeeyooooyaaaiii
A few minutes silence punctuated only by heavy breathing
Wendy: Oh Tony, you make boom-boom so good. You not rike Lupert. Him take Viagla, but still him linkry old cock useless, not stand up stlaight like you cock
Tony: Well, I’m a pretty straight kind of guy (Tony laughs at own joke)
Wendy: Tony, you Number One guy in world. Lupert old and lubbish man now. But you big Number One guy
Tony: (through gritted teeth) I wish. I could have been President of the EU. Boss of over 500 million people. I’d have been more important than the president of the USA. I’d have been great. If only we’d joined the f**k*ng Euro. They’d never make someone from outside the Eurozone EU president. That miserable f**k*ng boot-faced, Scottish f**wit Brown knew that. He knew I wanted to be EU president. That’s why he kept us out of the Euro. Just to spite me, the psychopathic sh*thead. And look what happened! Look who got the job I should have got! The damp, toe-rag Gollum lookalike, insignificant Belgian nobody Van Rompuy. I’ve got charisma, I’m a leader, I should have been the most important man in the world.
Wendy: But Tony, you velly big hitter. You get huge much money. Money number one…
Tony: No Wendy. It’s a f**k*ng disaster. Useless nonentity Van Rompuy gets the top job and I have to spend the rest of my life whoring myself out for just £20m to £30m a year to crap American banks and rotten, corrupt, oil-rich Third World tinpot dictators.
Wendy: No feel so angly Tony. Here. Let me gib you suckee suckee special Asian style. Make you whole much better.
(I cannot repeat the next 5 minutes as I have a family audience) Anyway, later
Wendy: Tony, Chelie she no mind you boom -boom me?
Tony: Cherie? That old witch (or it might be “bitch” – the recording is not exactly clear) doesn’t care what I do as long as the money keeps on rolling in and as long as she can keep on flaunting herself around the world’s movers and shakers.
Wendy: You Chelie velly rucky hab man rike you Tony. Me soon hab no man. Me divorce pathetic ord impotent Lupert. But me get velly much Lupert money. Lupert think he crever. But he just stoopid old foor – he like Asian pussy, now he gonna pay prenty much.
Tony: And I’m screwing his wife, just like I’ve screwed everyone else I’ve ever met Ha ha ha (Tony laughs at his own brilliance).
(No doubt, in today’s “take offence at anything Britain”, some readers will be offended by today’s post while others will think it just puerile. Hey ho, can’t please all of the people all of the time)
By David Craig, on November 26th, 2013 I have previously written about why we need to talk to our parents about their money. I imagine most readers thought either I was being excessively alarmist or else that as the people they knew over 60 were intelligent professionals, there’s no way they would allow themselves to be fleeced by financial services salespeople. If these were your reactions, you were wrong, very wrong.
Some facts:
Annuities – About 90% of annuities are mis-sold. This means annuitants are getting less money than they should every month for the rest of their lives. About 360,000 annuities are sold every year. So 324,000 a year (6,230 a week, 1,246 every working day) are mis-sold.
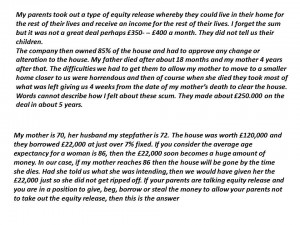
Equity Release – Equity Release is a fairly new product. When many people had final-salary pensions, there was little need for Equity Release. But as final-salary pensions have vanished and people are finding out how little there is in their retirement funds (due to high charges and poor investment performance) and how low annuity rates are, many are turning in desperation to Equity Release. We don’t know how widespread mis-selling is. But there’s no reason why it should be any less than with annuities (click on image to see clearly).
Dud investments – I wrote yesterday about how £60bn of savers’ money (usually older savers) has gone into worthless structured products sold by banks and another £75bn has gone into expensive unit trusts, 90% of which fail to even match overall stock-market performance due to their high charges.
There seem to be 3 main reasons why older savers are being constantly fleeced
1. They are part of Generation Trust – they come from a generation when you could trust you bank manager or pension adviser or financial adviser to look after your interests. So they fail to understand the levels of greed, dishonesty and corruption that are now rife in the sale of financial services
2. They’re too proud to admit problems – many older people are not used to talking to their children about their financial situation and are too proud to admit they are struggling. These makes them easy prey for people selling usurious equity release or dud investments
3. They’re vulnerable – Most of the country’s savings are owned by people approaching or already in retirement. Financial services insiders call them the “banana skin and grave brigade” because they have one foot on a financial banana skin (they know little to nothing about savings and investments) and one in the grave (so there’s no harm relieving them of their money before they go). Older people living increasingly isolated lives or on their own are particularly at risk as they’ll tend to be more accepting of a commission-based financial salesperson visiting them in their homes to flog them some supposedly ‘safe’ financial product. And people in retirement homes are also at risk as many retirement home managers have struck dirty little deals with financial sellers whereby they can come into the homes to sell their stuff and the manager(ess) gets a taxfree, cash in an envelope kickback from the seller.
The older generation are getting fleeced by the financial services industry. Don’t believe that just because someone had a successful active career that they’re immune. They’re not. In fact, they’re prime targets as they have confidence in their own judgement and so are more easily fooled.
You need to sit down with everyone you know who is over 60 and ask them “who is after your money?”. You have to find out which organisations – banks, investment companies (St James Place, Fisher Investments etc), equity release companies, boiler-room share sallers or whoever – have been soliciting them to get hold of their money. Then you have to explain why most of the stuff they are being sold is financial garbage designed to make the seller a lot richer than the buyer.
This is a difficult conversation to have. But if you do have it, you could save them from being thoroughly fleeced by today’s totally amoral financial services industry.
(Tomorrow – explosive stuff. A secret tape recording of two people called Wendy and Tony in the bedroom of a house owned by someone called Rupert. Don’t miss it!)
By David Craig, on November 24th, 2013 While those with mortgages may be partying over low interest rates, for those with savings, the Government’s attempts to lower the interest it pays on its ever-increasing debt (up from £700bn in 2010 to £1.4trn by 2015) are disastrous for anyone with savings.
You’ve probably read in the papers that savers are losing around £120bn a year in income from their savings because of low interest rates. But low interest rates have been even more damaging. Many people, who are risk averse and would never consider putting their money into stock-market investments, are being forced by low interest paid on bank accounts to move their money into supposed “investments” as they try to protect their money from inflation. (The Government claims inflation is only about 2.7% – probably it’s nearer 5%)
Since 2008/9, about £60bn of savers’ money has gone into investment products sold by banks and usually called something like “Guaranteed Growth Bonds” or “Guaranteed Investment Bonds”. I have previously explained why these are truly dreadful for savers but wonderful for the banks and City spivs who have created them www.snouts-in-the-trough.com/archives/7404
Up to 2008, we were putting about £10bn a year into unit trusts – since 2009 this has rocketed to £23bn a year, giving unit trust managers £75bn more than they would have got if interest rates had stayed at a normal level www.snouts-in-the-trough.com/archives/7414
So, that’s at least £135bn of our savings that have flowed out of things like 2- and 3-year fixed interest accounts and into risky stock-market schemes. Savers will be paying around 3% a year to the people who have sold these schemes and who manage their money. That’s an extra £4bn (£135bn x 3%). I don’t know how many people will benefit from this extra £4bn a year – let’s say it’s 5,000 at most (I suspect it’s fewer). Then splitting this £4bn amongst these 5,000 financial services insiders, that’s an extra £800,000 a year each – all due to desperate savers moving money from relatively safe bank accounts into financial products developed by City spivs to make themselves rich at ordinary savers’ expense. Low interest rates have certainly been rather good for the Tories’ friends in the City.
Equity Release – A couple of days ago I wrote a piece warning of the dangers of Equity Release www.snouts-in-the-trough.com/archives/7529 . Here’s another reader’s story:
“Dear David. Been away so I have only just read your article about equity release. My parents took out a type of equity release whereby they could live in their home for the rest of their lives and receive an income for the rest of their lives. I forget the sum but it was not a great deal perhaps £350- – £400 a month. They did not tell us their children. The company then owned 85% of the house and had to approve any change or alteration to the house. My father died after about 18 months and my mother 4 years after that. The difficulties we had to get them to allow my mother to move to a smaller home closer to us were horrendous and then of course when she died they took most of what was left giving us 4 weeks from the date of my mother’s death to clear the house. Words cannot describe how I felt about these scum. They made about £250.000 on the deal in about 5 years.
It was painful to lose the money I must admit, but much more painful was trying to get them to allow my mother to move to be closer to us in her last days. They are inhuman”
By David Craig, on November 24th, 2013 I know some readers will be upset by my descent into “smut”. But I’ve written 1,242 posts on this website and I think only about 5 or 6 (less than 0.5%) have mentioned s*x.
Any way there’s good news for those of us who find s*x tourism rather questionable. Many girls don’t want to do it any more.
Here in the Land of Sm*les, it has long been the tradition in poor families that the daughters leave school early to work and provide for their families while the sons stayed in school to get an education and then hopefully a job. Given that most girls had no qualifications, many had little choice but to move into the s*x industry to live up to their family obligations.
However, things are slowly changing – for the better. With economic growth, there are fewer very poor families, so more girls are staying in school for longer and then are getting proper jobs in factories and offices. This is causing a huge problem for gogo bar owners – they’re finding it increasingly difficult to get the staff they need to pull in the punters.
I was talking to one manager a couple of days ago. “It’s a disaster”, he explained, “girls don’t want to dance in bars any more. We’ve been forced to increase wages, but still we can’t get enough good-looking ones”. He went on to lament the fact that even when he could get girls, they wanted to dance in their bikinis and wouldn’t even take their tops off to show their breasts. As for dancing naked, which used to be the norm, very few would agree to this. Even worse for him, he needed girls to do what he called “the naughty stuff” – pushing various objects including bananas and rubber penises into themselves and letting men do all sorts of things to them – it was almost impossible to find any girls who would do that nowadays.
The traditional image most male s*x tourists have of the Land of Sm*les is probably like this:

But, in fact, many (maybe even most) of the girls still in the industry are long since past the first flush of youth and some are even matronly rather than nymphettish. An awful lot seem to have had at least one, and often several, children which doesn’t do wonders for your body and makes dancing naked for 7 to 8 hours a day not a viable proposition – hence they prefer to keep as many of their clothes on as possible.
However, the gogo bar owners are not giving up. In a couple of years, the main Asian countries are starting their own Common Market – a free trade and free movement area (without the political and bureaucratic monstrosity that is ruining Europe). This will mean that girls from poorer countries like Myanmar, Laos and Cambodia should be able to come and work in the Land of Sm*les – providing lots of fresh young meat for the gogo bar owners.
As for European female sex tourists, the lack of economic progress in Africa and the Carribbean means they’ll still be able to enjoy the pleasures they can’t get at home in dreary old Britain

By David Craig, on November 23rd, 2013 I don’t know if you’ve ever watched Formula 1 (F1) racing. I tried a couple of times then gave up at the sheer boredom. Apparently years ago the cars used to actually race each other and sometimes even overtake. But now the race is like a high-speed procession. Half of all races are won by the car that starts in pole position. Almost all races are won by the car that starts in pole, second or third position. So you pretty much know who is going to win the race even before it has started.
The commentators try to inject some excitement into this procession. And when the leading car goes in for a pit stop, the order does change for a few minutes. But then the other cars go in for their pit stops and the original procession resumes. So how can you make squillions from a product that is only slightly more exciting than watching paint dry? That’s the genius of Bernie Ecclestone.
What he has done, as far as I can see, is go to some developing countries. These are usually countries that have contributed little or nothing to human advancement in science, technology or the arts. Countries that wouldn’t recognise a Nobel Prize if it hit them in the face. And Ecclestone has, I think, sold these countries on the story that if they give him piles of cash, he’ll hold a F1 Grand Prix in their country and that will make their country seem modern and developed.
Thus we got the Malaysian Grand Prix in 1999. In 2004 both China and that great world power Bahrain handed over their cash to join the Grand Prix club. In 2005 that beacon of development and modernity Turkey held its first race. In 2009, that leading international powerhouse and centre of scientific advancement Abu Dhabi signed up. Then in 2010 there was Korea and in 2011 India – one of the most corrupt unequal countries outside of Africa.
So where will F1 go next? What about Africa? There’s oil-rich Nigeria. They have loads of money even though 90% of the population live in poverty. Or Equatorial Guinea – again gazzillions of money even though 98% of the population live in abject poverty. Yup, Africa seems to provide just what F1 is looking for – countries with heaps of money and nothing to show for that money apart from corruption. backwardness and oppression.
Although, perhaps I shouldn’t criticise the (in my opinion pointless) F1. Over 500 million people apparently watch it. That’s rather more (unfortunately) than read my website or books.
If I may, I’d like to publish 2 comments readers sent me following my blog yesterday warning about the dangers of Equity Release loans:
“In certain circumstances equity release is a great idea. Take your asset rich cash poor couple for example. If they don’t want to trade down and have no children what’s wrong with taking a bit of equity out?”
“Another gem. Why is it, that when we become old we are sitting ducks for all and sundry? Ten years ago my friends were short on cash, and they asked my opinion about Equity Release. I told them to keep well away, and gave them an example of interest growth. They were astounded. Their daughter came up with the solution. She increased her mortgage, and saved herself a load of grief.”
By David Craig, on November 22nd, 2013 Apologies if today’s post is not directly relevant to you in your financial situation at your time of life. But we all know people who are either about to retire or who are retired. What we probably don’t know – because people of that generation are often reluctant to talk about money – is that these people are being aggressively, even viciously targeted by Equity Release companies.
As part of my research for my next book, I went to a supposedly free seminar recently all about ensuring “a financially secure retirement“. In fact it was just a hard sell session for Equity Release. What was deeply worrying was the queue of people at the end all signing up to arrange for the salesman to visit them in their homes to discuss them taking an Equity Release loan.
What is Equity Release? Many older people are what financials services companies call “asset rich, cash poor“. They have houses (assets) which may be worth quite a lot of money. But because their pensions have performed so badly and because annuity rates and interest rates are so low, these people may be struggling to find enough money to have a comfortable retirement. They have a tough choice – sell their homes to generate some cash or continue to struggle. This makes them perfect targets for smooth-tongued, unscrupulous salespeople proposing that these people can stay in their homes by taking out a loan against their homes – a loan that doesn’t have to be repaid till they either move into a nursing home or die. Sounds pretty good!
So what’s wrong with Equity Release? The interest rates. Interest rates on Equity Release are only a couple of percentage points above a mortgage. So they sound like a good deal. But over 15 to 20 years, this small difference in interest rate can add up to a huge amount of money.
Just one example – if someone takes out an Equity Release loan of £53,000 (that’s the average size) when they’re 66, they’ll owe about £200,000 by the time they’re 86. In comparison, if their children had added £53,000 to their mortgage (to help their parents out), then they would only have had to repay about £95,000 over 20 years. So the family (parents and children) would be £105,000 better off (£5,000 a year) if that £53,000 loan had been added to the children’s mortgage rather than being taken out as an expensive Equity Release loan.
Let me give you a quote from a family which found out their parents had been conned into taking out an Equity Release loan:
My mother is 70, her husband my stepfather is 72. The house was worth £120,000 and they borrowed £22,000 at just over 7% fixed. If you consider the average age expectancy for a woman is 86, then the £22,000 soon becomes a huge amount of money. In our case, if my mother reaches 86 then the house will be gone by the time she dies. Had she told us what she was intending, then we would have given her the £22,000 just so she did not get ripped off. If your parents are talking equity release and you are in a position to give, beg, borrow or steal the money to allow your parents not to take out the equity release, then this is the answer.
Hopefully that’s pretty clear.
Each month or so I get a booklet from an Equity Release company – I think it’s called Retirement Solutions – pushing Equity Release and full of stories of happy, healthy pensioners who have been able to take the holiday of a lifetime, visit their grandchildren in Australia, Canada or wherever, finish a home extension etc etc thanks to the generosity of the Equity Release business. Just wait till payback time comes and see how happy and smiling they are when they find out that a small, supposedly manageable loan has mushroomed into a mountain of debt that will leave their heirs penniless.
Equity Release may work for a few people – those who intend to leave little to nothing for their children or relatives after their deaths and who don’t plan to save anything for care home fees. But for most people, it’s an expensive disaster. So, please please talk to any retired people you know, ask if they’re being pestered by Equity Release salespeople and warn them that seemingly small Equity Release loans can wreck their family’s financial future (while ensuring a comfortable living for the Equity Release seller).
(If any readers or people readers know have taken out Equity Release, I’d be interested to know if they’re satisfied or whether they’ve realised that they’ve made a serious financial error. I’ll publish any answers)
|
|