|
|
By  David Craig, on September 28th, 2012 We’re constantly being told that putting our money in shares through unit trusts or pensions or ETFs or OEICs or whatever, will make our savings grow in the long run. Article after article in the Money pages of our newspapers use projections of 5% or 6% a year to show how our savings will increase. But these articles never mention if the enticing 5% or 6% a year growth rates are before or after inflation.
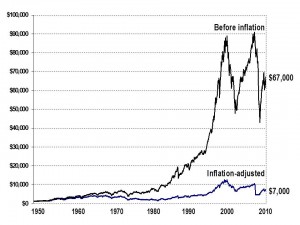
If you’d put $1,000 into US shares in 1950, you’d now be sitting on a wonderful $67,000. But knock out inflation and this becomes just $7,000. Bottom line – in 60 years your savings have hardly grown at all (see diagram below). The situation is similar for UK shares. And few of us save for 60 years.
Moreover, note that most of the market growth came in the 1980s and 1990s when babyboomers were at their earnings and savings peak. When babyboomers start retiring and buying annuities, their money will come out of shares and into government bonds – shares will stagnate or fall. So don’t believe the “your money could grow by 6% a year” lies from the people who want to get hold of your cash.
By David Craig, on September 27th, 2012 When the idiots Gordon Brown and Ed Balls took over the Treasury in 1997, our national debt was about £300bn. By 2010 when these fools were booted out, our debt was over £700bn. It is now over £1trn. Whatever the Coalition does or doesn’t do, debt will reach £1.6trn by 2015/16. Our interest payments will soon hit £60bn a year – more than we pay for defence or education. We are going slowly and horribly bankrupt.
But there is light at the end of the tunnel – for our incompetent, over-paid, over-pensioned, expenses-thieving politicians – though not for us. We have over £3.5trn in savings – £500bn in unit trusts, £800bn in pensions, £500bn in higher-interest bank accounts and another £1.7trn in other bits and pieces. If our worthless, self-serving politicians could get hold of this money, then their problems would be solved.
Our incompetent politicians are already salivating at the thought of taking and wasting the £800bn we have in pension savings. Osborne tried to steal over £30bn of this money claiming he should use ‘British savings for British jobs’. If he does take this money, most will be wasted and most of the jobs will go to foreigners. Now Clegg is proposing to pressure us to use our pension savings to buy houses for our children and grandchildren in the ridiculous belief that maintaining housing at historically unaffordable levels will somehow boost the economy. What Clegg knows about economics could be written on the back of a very small postage stamp.
But this is only the start. When the bulging-eyed buffoon Ed Balls becomes chancellor in 2015, the theft of our savings will move up a few gears. Under the banner of ‘fairness’, Balls will find some way of grabbing our money to squander on more public-sector non-jobs and higher salaries for our millions of unnecessary bureaucrats. Then under the banner of ‘everyone is entitled to dignity in retirement’, he will impose punitive taxes on our pension savings to give our money to those who didn’t earn enough or couldn’t be arsed to save for their own retirement.
Beware – the coming Taxmaggedon is going to decimate any money you manage to save. But our greedy, incompetent, self-serving politicians and bureaucrats will continue to live a life of luxury at our expense.
By David Craig, on September 26th, 2012 The Labour and Tory governments’ favourite management consultancy, McKinsey, is pocketing millions or even tens of millions of pounds of our money imposing a top-down reorganisation of the NHS that will increase bureaucracy and waste. This is after the Tories promised us there would be no more top-down reorganisations of the NHS and that they would reduce NHS bureaucracy and waste. But judging from a song reportedly sung at a McKinsey consultants’ Christmas party, McKinsey’s millionaire consultants don’t think much of their clients – us and our government. (I believe this should be sung to the tune of Hark the herald angels sing, repeating the last two lines of each verse as a chorus)
If you aim to get the best result
And maximum performance you want to see
Then you really should consult
A Management Consultancy
McKinsey management consultants are we
We take all our clients’ money
We can earn many a million
Because our clients have no vision.
If Process Redesign is what you will
And you think it’ll make a success of all you do
Then rely on us to send you a bill
While we redesign your processes for you.
We are from McKinsey – young, bright and flash
We take mountains of our clients’ cash
We win lots of new clients rich and fine
When we go round flogging Process Redesign
We’ve got handouts and we’ve got flip charts
And dazzling PowerPoint presentations
And we blow clients away
With our brilliant explanations.
We are McKinsey’s little lackeys
Telling clients they’re in trouble is just one of our strategies
Our language is smart and makes our clients ill-at-ease
– It’s what we call ’Consultantese’.
The culture at ……. is a real dead weight
But we crush resistance before it grows
We’re used to organisations in a dreadful state
Because, of course, we are Pros!
We are McKinsey’s real hard core
We are the ones who’ll win the war
Now we’re going to party and have fun because
Cheers! We’ve just got our bonuses from Santa Claus.
By David Craig, on September 25th, 2012 There are over 100,000 people in Britain claiming to be ‘financial planners’. But most, whether working for banks or as supposedly ‘independent’ financial advisers (IFAs), are just glorified salespeople out to put as much of your money as they can into the investment schemes which earn them the highest commissions. One study of IFA customers found that not one had what could be called a ‘financial plan’
A simple plan (see below) might consist of a spreadsheet (on computer or paper) where you lay out all the years from where you are till when you expect to die. Then you would have a series of lines with your expected income, expenses, pension savings and amount available for luxuries. (To estimate the growth in your savings you should probably do two projections – at 3% and 5%). Unless you’re very lucky, you might find out that you’re not going to be going on many world cruises when you finally (if ever) stop work. Making a financial plan can be a very sobering experience, but you might not stay sober for long.

By David Craig, on September 24th, 2012 We should be grateful to our foul-mouthed superior Andrew ‘I’m a multimillionaire’ Mitchell. He’s the first Tory to be honest about how our government of arrogant, self-important, self-serving, lying, expenses-thieving multimillionaires views the people who are stupid enough to vote for them and pay taxes to support their luxury lifestyles. We really are just a bunch of ‘f–king morons’ and ‘plebs’.
Twenty years ago you needed just £50m to join the Sunday Times richest 200. At the start of the recession this had shot up to £430m. Since the recession, this has risen again to over £450m. The rich really have had a very good boom and an even better bust. As for our MPs, while bleating that they only earn £65,000 a year, most of them (like Andrew Mitchell) are really pocketing hundreds of thousands of pounds a year from second, third and fourth jobs, plus they are now claiming around £40,000 a year each more in expenses than before the expenses scandal broke. Below is a graph showing how our multimillionaire rulers are making fools of us f–king moronic plebs.

By David Craig, on September 23rd, 2012 The people that banks and financial advisers seem to find most attractive are what some in the financial services industry call the ‘banana skin and grave brigade’ – elderly people who have one foot on a financial banana skin as they don’t know much about finance, savings and investments and the other in the grave as they’ll soon be going on to a better place where they won’t be needing their money any more so there’s no real harm done relieving them of their cash before they depart. As many of the banana skin and grave brigade will have worked all their lives and saved by buying homes, pensions, life insurance, unit trusts and other assets, they tend to control a large proportion of national wealth.
The two things the elderly usually fear most are outliving their savings and becoming so unwell that they have to sell their homes to pay for nursing-home care. This makes them easy targets for advisers with both products like annuities promising guaranteed income and thus peace of mind and with all sorts of more complex investments advertising (but not guaranteeing) high returns. Some sellers use what they call ‘FAG selling’ (‘Fear and Greed) – they exploit older people’s fear of lasting longer than their money and their greed when offered opportunities to increase their savings.
Many financial advisers specialise in the lucrative market of selling to retirees and those planning their retirement. They can have titles like ‘senior wealth advisers’, ‘retirement planning advisers’, ‘elder planning specialists’ or even the rather scientific-sounding ‘financial gerontologist’. One set of dubious products typically sold and mis-sold to the banana-skin-and-gravers were longer-term (five or more years) stock-market investments with punitive penalties for early withdrawal. These were recommended to both men and women in their late seventies and mid eighties when the average life expectancy for men and women was around eighty six. Naturally, quite a few customers with the longer-term stock-market products died before their investments matured and their heirs found that, after deduction of early-withdrawal penalties, the investment companies returned considerably less than had been invested.
If the elderly don’t have much ready cash available, that hasn’t deterred eager financial sellers. Although some over-65s may have limited pensions and savings, many own their own homes making them what’s called ‘asset-rich but cash-poor’. Seeing the potential of the asset-rich cash-poor market, financial firms have devised various schemes, often called ‘equity release’, which promise to free up some or all of the value in their customers’ homes allowing them to live more comfortably till they die in return for the firms taking part or whole ownership of their customers’ properties.
Interest rates on these loans tend to be significantly higher than on a mortgage, so thanks to the wonders of compound interest, even sums that appear quite modest when originally borrowed can turn into massive debts. For example, someone aged sixty five borrowing the average equity release loan of £50,000 against a home worth £200,000 would find their debt had shot up to about £100,000 after ten years and £200,000 – the total value of their home – by the time they hit eighty five.
In Britain we feel uncomfortable talking about money with our parents and elderly relatives. We feel it might look like we’re on a fishing expedition trying to find our how much money we might get. But if you want to prevent those you know becoming part of the ‘banana skin and grave brigade’ we need to overcome our reticence, ask our elderly friends and relatives about their money, find out who is chasing them to get hold of their cash and warn them about the dangers of handing over their savings.
By David Craig, on September 23rd, 2012 In a sickeningly sycophantic article in the Sunday Torygraph, a supposed journalist (probably one of Andrew Mitchell’s mates) claims that Andrew Mitchell is a ‘decent man’ who would never use the word ‘plebs’ or swear at the police. Unfortunately, in another article the ghastly (in my opinion) Mitchell admits he did swear at the police. As far as I can see, the repulsive (in my opinion) Mitchell is an arrogant, overbearing, self-important, self-serving, bullying thug – just like most MPs.
So, dear Torygraph sycophants, please spare us your lickspittle, grovelling apologia for your friends in high places
By David Craig, on September 22nd, 2012 First Cameron gives in to Clegg by bringing LibDem liar and thief David Laws back into government. Then gutless Cameron doesn’t have the balls to sack the repulsive Andrew Mitchell. Tells us all we really need to know about our spineless, lying, hypocritical, incompetent prime minister. The sooner PR spiv Cameron resigns to spend more time with his money, the better for all of us.
By David Craig, on September 22nd, 2012 The main high-street banks (HSBC, Barclays, NatWest, Lloyds etc) love to run our current accounts. They don’t make too much money from this. But it gives them the chance to do what they call ‘cross-selling’ – using their contacts with us and information about us to flog us all kinds of other financial products. These include deposit accounts, mortgages, insurance, pensions, investments and so on. But, apart from some very rare exceptions, you’d be a fool to buy any of these products from your high-street bank.
For deposit accounts you’ll usually get much better rates from the former building societies. Mortgages – it’s normally better to go to a specialist mortgage broker. Insurance – why pay a large commission to your bank, when you can buy more cheaply direct (on-line) from an insurance company? Pensions – anyone saving with a high-street bank is going to pay so much in charges that they’re going to end up awfully poor. Investments – time after time it has been shown that banks (especially Barclays and HSBC) have cobbled together and mis-sold appalling investment schemes which have made billions for the banks and lost billions for their gullible customers.
At the moment, many banks are enthusiastically flogging what are often called ‘Growth Bonds’ or ‘Guaranteed Bonds’. These promise to pay around 120% of stock-market index growth for a five- or six-year period and guarantee to return all a saver’s capital even if the index falls. About £58bn of our money has gone into these awful products. What too many savers don’t understand is that almost all the benefits of stock-market investing come from the dividends paid by the companies whose shares are bought and not from any movements in the overall market. Yet these products only pay out on increases in the market index. Most savers will get back less than they would have earned just leaving their money in an ordinary bank account, but the banks have pocketed £1.5bn of our money selling these products and a further £580m a year in ‘trailing’ commission.
So the lesson is – ‘only bank with your bank’. Only let your high-street bank run your current account. If you do any other business with the likes of HSBC, Barclays, RBS, Lloyds, NatWest then the chances are that you are a fool and are paying for over-priced, poorly-performing products.
By David Craig, on September 21st, 2012 As Libdem leader Nick Clegg becomes a figure of even greater ridicule and contempt following his ‘I’m sorry’ video, people might not be laughing quite so much if they realised how much this lying buffoon is going to cost us.
Let’s assume that Clegg spends 30 years siphoning our money into his own pockets – first as an MEP, then MP, then Deputy Prime Minister, then no doubt he’ll find some sinecure in Brussels or else runnng some pointless quango. If he costs us £300,000 a year in salary, expenses, staffing and office costs, that’s £9 million we’ll be paying. Then, when he retires he’ll probably be picking up a pension of say £100,000 a year for another 30 years – another £3 million of our taxes.
Then we must add the tens of millions Clegg will have wasted. His pathetic AV referendum cost us about £80 million. Clegg blocked Cameron’s plan to reduce the number of MPs from 650 to 600, so that’s 50 completely unnecessary MPs we’ll be paying for – £15 million a year for say thirty more years – £450 million.
All in all, the lying, incompetent, self-serving Clegg will cost us taxpayers at least £542 million. That’s an awful lot of money. Is Clegg really worth it?
|
|