|
|
By  David Craig, on October 4th, 2012 As the number of Western troops killed by Afghans in military or police uniforms rises, our media keep referring to the Afghans as either “rogue soldiers” or “rogue policemen”. But are they? Or are they in fact courageous freedom fighters prepared to give their lives to rid their country of a foreign army of occupation put in place to support a corrupt, incompetent, drug-dealing puppet government?
I never thought I’d agree with anything written in the dreadful Guardian. But Simon Jenkins’ article dares to call a spade a spade, a futile fiasco a futile fiasco, a defeat a defeat and a retreat a retreat. I highly recommend it:
https://www.guardian.co.uk/commentisfree/2012/oct/02/why-british-soldiers-dying-in-afghanistan
By David Craig, on October 3rd, 2012 Hopefully, you’ll have found some of the information in my blog informative from time to time. If so, I’d like to ask a favour.
My latest book GREED UNLIMITED How Cameron and Clegg protect the elites while squeezing the rest of us has just been published. If I had done the book with a traditional publisher, it wouldn’t have come out till late spring 2013, by which time it would have been out of date. The reason is that the main bookshops – Waterstones, WH Smith and Blackwells – buy books six months ahead.
To get the book out in reasonable time, I’ve had to publish it at my own expense. The problem is then that I can’t get any orders from WH Smith or Waterstones (unless customers go in and order the book). But I can sell through amazon.co.uk and the Waterstones, WH Smith, Blackwells and other book-selling websites as they get copies direct from the wholesalers when people buy them.
I need to sell about 600 copies to break even. Less than that and I lose my shirt. So if you can help by buying copies for yourself or friends and family and/or telling other people about the book, that would be very much appreciated.
The book colourfully takes apart the hopeless Cameron/Clegg/Osborne conspiracy of incompetence while also lambasting the useless Miliband/Balls dumb duo. In fact, it rips into the whole ruling establishment of politicians, bureaucrats, business bosses and bankers – so it’s not bad value for six or seven quid (the price of a couple of pints).
It’s available as a paperback, Kindle version or eBook. Many thanks for your help with this.
David Craig
By David Craig, on October 2nd, 2012 This government, like all governments, wants to tax us more so it can spend and waste more while the 29,000 (yes you read that correctly – 29,000) people in the political classes (politicians, staff and hangers-on) stuff their pockets with our money. Tax rises are unpopular, but our political masters are good at disguising tax increases.
The latest government trick to get more of our money is to force people into pension savings. For anyone earning less than £25,000, making any pension savings will be a waste of money. They’ll have so little by the time they retire that the only result of having a few thousand pounds saved up will be to deprive them of benefits available to people on the basic state pension. So their savings will save the government money, but be utterly futile for them.
If I understand the situation, the state pension is about £96 a week. But if you don’t have any other income, you can claim at least another £60 a week in benefits. Pensions savings of £100,000 will buy you an inflation-linked annuity of about £3,500 a year (£70 a week). But if you have managed to save £100,000 (the average pensions savings are just £40,000) you’re going to lose about £3,000 a year (£60 a week) in benefits.
However, another 10 million or so people putting a tiny percentage of their meagre earnings into the hands of multimillionaire pension fund managers will make the City spivs who fund the Tories an awful lot richer. After all, 10 million people saving say just £500 a year each will give City spivs £5bn a year. If they siphon off even just 1.5% in fees and dealing costs, that’s £75m in the first year for doing hardly anything. £150m in the second year and a glorious £750m a year in fees by year ten of the government’s great scheme.
So the bottom line is – if you are unlikely to save significantly more than £100,000 in your pension by the time you retire, you should opt out of the Government’s pension scheme/scam. This means that around 70% of people should avoid the new scheme/scam as all they’ll be doing is handing even more of their money to be wasted and stolen by politicians, bureaucrats and bankers.
By David Craig, on October 1st, 2012 The (in my opinion) slimey, careerist, self-serving, political opportunist Jack Straw is busy promoting his memoirs. He now reveals that he always thought Gordon Brown would make a dreadful PM. But, in spite of what he knew about Brown, Straw ran Brown’s campaign to become PM. Greater love hath no man for himself than he will lay down his country for his own career.
I suppose you have to admire Ed Balls. Few people could keep a straight face doing what he’s doing. After having helped the worthless liar Brown bankrupt Britain by wasting about £1.5trn of our money, Balls is trying to present himself as being financially responsible. Perhaps he’ll have his fingers crossed behind his back when he gives his conference speech?

The (in my opinion) truly repulsive, bejeweled creature Angela Knight spent years lucratively defending lying, thieving bankers against any criticism. We have now found out that almost everything she said could appear (to someone like me) to be a bunch of lies. Now this person has moved on to a new job, defending rip-off energy companies against justified criticism that they are fleecing their British customers. But the facts (see diagram) show we are being well and truly screwed. About half our energy companies are foreign-owned and see Britain as a goldmine as they are tightly regulated in their home countries. But the useless Ofgem lets them make massive profits here that they aren’t allowed to make in their countries of origin.
By David Craig, on September 30th, 2012 Our clueless, expenses-thieving politicians and their sycophantic, careerist ‘advisers’ (actually just the next generation of self-serving, professional politicians) are completely clueless about what to do as public spending spirals up out of control and tax revenues plummet.
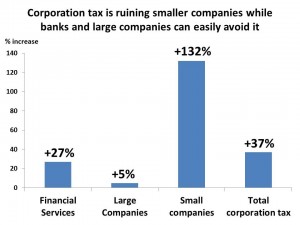
One part of the answer can be found in the simple diagram below. This shows that during the 1997-2007 Brown/Balls boom, the tax paid by small companies (SMEs) shot up by 132%. Yet while making massive profits, the tax paid by financial services companies only went up by 27% and tax paid by our largest, usually multinational companies, only crept up by a pathetic 5%. The reason for such a gap between the increase in SMEs’ tax compared to that of financial services and largest companies is that SMEs cannot use all the tax avoidance tricks used by banks and multinationals.
I’ve written before that most taxes only have a brief usual life before those being taxed find ways to avoid paying them. In the past we’ve had hearth taxes, beard taxes, window taxes and hat taxes. All were abandoned when people changed behavious and revenues fell. I believe that Corporation Tax is also past its useful shelf-life. It is an unfair burden on Britain’s 4.5 million SMEs while larger companies can almost ignore it. It’s time to scrap Corporation Tax and replace it by a tax on all business activities conducted in the UK – basically, the Government should retain part of VAT normally reclaimed by businesses. Then companies would be forced to pay tax whether they claim to be based in Jersey, the Cayman Islands or on the Moon.
Why are our politicians too stupid to understand this? Perhaps you could forward this link to your MP?
By David Craig, on September 29th, 2012 Thanks to the spinelessness of liar Cameron, the incompetence of work-experience Osborne and the stupidity of Clegg, the public-sector unions’ whore (in my opinion) Ed Miliband will be standing outside 10 Downing Street waving to the crowds in just 30 months. The party that almost bankrupted Britain will be back to completely destroy the country.
The bulging-eyed buffoon Ed Balls, who helped the liar and fool Brown wreck our economy, will become chancellor. Balls understands just how stupid British voters are and so is now implausibly claiming he will take a hard look at public spending. This is rubbish. During the Brown boom, tax revenues went up 75%. Brown and Balls could have increased public spending by 70% and also paid back all our national debt. But Brown and Balls, more than doubled public spending from £322bn to £750bn and blew another £300bn on overpriced, underperforming PFI projects that are now bankrupting many hospitals and schools.
In all, during the boom and bust, Brown and Balls destroyed around £3.25 trillion of Britain’s wealth (see diagram). God help us when the repulsive, incompetent Balls gets his hands on our economy again.

By David Craig, on September 28th, 2012 We’re constantly being told that putting our money in shares through unit trusts or pensions or ETFs or OEICs or whatever, will make our savings grow in the long run. Article after article in the Money pages of our newspapers use projections of 5% or 6% a year to show how our savings will increase. But these articles never mention if the enticing 5% or 6% a year growth rates are before or after inflation.
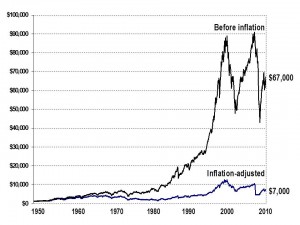
If you’d put $1,000 into US shares in 1950, you’d now be sitting on a wonderful $67,000. But knock out inflation and this becomes just $7,000. Bottom line – in 60 years your savings have hardly grown at all (see diagram below). The situation is similar for UK shares. And few of us save for 60 years.
Moreover, note that most of the market growth came in the 1980s and 1990s when babyboomers were at their earnings and savings peak. When babyboomers start retiring and buying annuities, their money will come out of shares and into government bonds – shares will stagnate or fall. So don’t believe the “your money could grow by 6% a year” lies from the people who want to get hold of your cash.
By David Craig, on September 27th, 2012 When the idiots Gordon Brown and Ed Balls took over the Treasury in 1997, our national debt was about £300bn. By 2010 when these fools were booted out, our debt was over £700bn. It is now over £1trn. Whatever the Coalition does or doesn’t do, debt will reach £1.6trn by 2015/16. Our interest payments will soon hit £60bn a year – more than we pay for defence or education. We are going slowly and horribly bankrupt.
But there is light at the end of the tunnel – for our incompetent, over-paid, over-pensioned, expenses-thieving politicians – though not for us. We have over £3.5trn in savings – £500bn in unit trusts, £800bn in pensions, £500bn in higher-interest bank accounts and another £1.7trn in other bits and pieces. If our worthless, self-serving politicians could get hold of this money, then their problems would be solved.
Our incompetent politicians are already salivating at the thought of taking and wasting the £800bn we have in pension savings. Osborne tried to steal over £30bn of this money claiming he should use ‘British savings for British jobs’. If he does take this money, most will be wasted and most of the jobs will go to foreigners. Now Clegg is proposing to pressure us to use our pension savings to buy houses for our children and grandchildren in the ridiculous belief that maintaining housing at historically unaffordable levels will somehow boost the economy. What Clegg knows about economics could be written on the back of a very small postage stamp.
But this is only the start. When the bulging-eyed buffoon Ed Balls becomes chancellor in 2015, the theft of our savings will move up a few gears. Under the banner of ‘fairness’, Balls will find some way of grabbing our money to squander on more public-sector non-jobs and higher salaries for our millions of unnecessary bureaucrats. Then under the banner of ‘everyone is entitled to dignity in retirement’, he will impose punitive taxes on our pension savings to give our money to those who didn’t earn enough or couldn’t be arsed to save for their own retirement.
Beware – the coming Taxmaggedon is going to decimate any money you manage to save. But our greedy, incompetent, self-serving politicians and bureaucrats will continue to live a life of luxury at our expense.
By David Craig, on September 26th, 2012 The Labour and Tory governments’ favourite management consultancy, McKinsey, is pocketing millions or even tens of millions of pounds of our money imposing a top-down reorganisation of the NHS that will increase bureaucracy and waste. This is after the Tories promised us there would be no more top-down reorganisations of the NHS and that they would reduce NHS bureaucracy and waste. But judging from a song reportedly sung at a McKinsey consultants’ Christmas party, McKinsey’s millionaire consultants don’t think much of their clients – us and our government. (I believe this should be sung to the tune of Hark the herald angels sing, repeating the last two lines of each verse as a chorus)
If you aim to get the best result
And maximum performance you want to see
Then you really should consult
A Management Consultancy
McKinsey management consultants are we
We take all our clients’ money
We can earn many a million
Because our clients have no vision.
If Process Redesign is what you will
And you think it’ll make a success of all you do
Then rely on us to send you a bill
While we redesign your processes for you.
We are from McKinsey – young, bright and flash
We take mountains of our clients’ cash
We win lots of new clients rich and fine
When we go round flogging Process Redesign
We’ve got handouts and we’ve got flip charts
And dazzling PowerPoint presentations
And we blow clients away
With our brilliant explanations.
We are McKinsey’s little lackeys
Telling clients they’re in trouble is just one of our strategies
Our language is smart and makes our clients ill-at-ease
– It’s what we call ’Consultantese’.
The culture at ……. is a real dead weight
But we crush resistance before it grows
We’re used to organisations in a dreadful state
Because, of course, we are Pros!
We are McKinsey’s real hard core
We are the ones who’ll win the war
Now we’re going to party and have fun because
Cheers! We’ve just got our bonuses from Santa Claus.
By David Craig, on September 25th, 2012 There are over 100,000 people in Britain claiming to be ‘financial planners’. But most, whether working for banks or as supposedly ‘independent’ financial advisers (IFAs), are just glorified salespeople out to put as much of your money as they can into the investment schemes which earn them the highest commissions. One study of IFA customers found that not one had what could be called a ‘financial plan’
A simple plan (see below) might consist of a spreadsheet (on computer or paper) where you lay out all the years from where you are till when you expect to die. Then you would have a series of lines with your expected income, expenses, pension savings and amount available for luxuries. (To estimate the growth in your savings you should probably do two projections – at 3% and 5%). Unless you’re very lucky, you might find out that you’re not going to be going on many world cruises when you finally (if ever) stop work. Making a financial plan can be a very sobering experience, but you might not stay sober for long.

|
|