|
|
By  David Craig, on March 21st, 2014 I first read this story on the Voice of Russia website. So, I assumed that it was just invented anti-EU propaganda. But it turns out that the story is actually true www.thetimes.co.uk/tto/news/uk/article4001000.ece
Mr Barroso and his fellow corrupt, self-serving, greedy, unelected komissars have come up with a brilliant new plan to boost economic growth in the stagnant EU which is being crushed by their economically-illiterate policies. Hooray for Barroso! Maybe he’s about to deliver our EU masters’ promise to us: “the Euro will lead to full employment and make Europe the competitive powerhouse of the world“.
Here’s Barosso’s plan: The EU is enforcing rules which require countries to estimate how much cash changes hands on their black markets. Those figures will be taken into account when calculating national GDP and allocating the £120bn Brussels budget.
The EU officials say the change will ensure consistent economic comparisons between member states.
As prostitution and drug use is legal in some member states, like the Netherlands and umm the Netherlands and there’s also umm errr the Netherlands, officials say it is only fair for other states to include these activities in their national accounts.

Prostitution in the UK is expected to be valued at £3bn/year and drug dealing at around £7bn.
Rules from 1998 say criminal activity should be included in GDP calculations. But until now the rules have been ignored. The UK Office for National Statistics will reveal statistics for the size of the illegal industries this spring.
The £10bn inclusion of criminal industries will have a trivial impact on the UK GDP which currently stands at £1.6trn. But the change will make a big difference to poorer countries, particularly the Club Med states, where people in their desperation are more likely to have turned to drugs and/or prostitution, pushing up their GDP by several percentage points and increasing their share of the EU pie.
Greece tried to exploit the rule in 2006. Officials doctored their figures to try and reduce the budget deficit. Economic gains from prostitution, drugs and money laundering caused the country’s GDP to shoot up by 25% overnight.
But last spring the European Parliament insisted it was time for other countries to follow the rules. These require countries to include only those illegal activities where a transaction takes place between two willing parties. Robbery, kidnapping for a ransom and blackmail, for example, will not count.
One interesting point this story raises is: if it was mentioned on the supposedly biased Voice of Russia, why wasn’t it mentioned on the supposedly unbiased BBC?
(Tomorrow – a shocking message/warning from President Putin)
By David Craig, on March 20th, 2014 Apologies if today’s post is not relevant to you. But if you’re approaching retirement or know someone who is close to retirement or know someone who has retired within the last 10 years, it might be worth reading on.
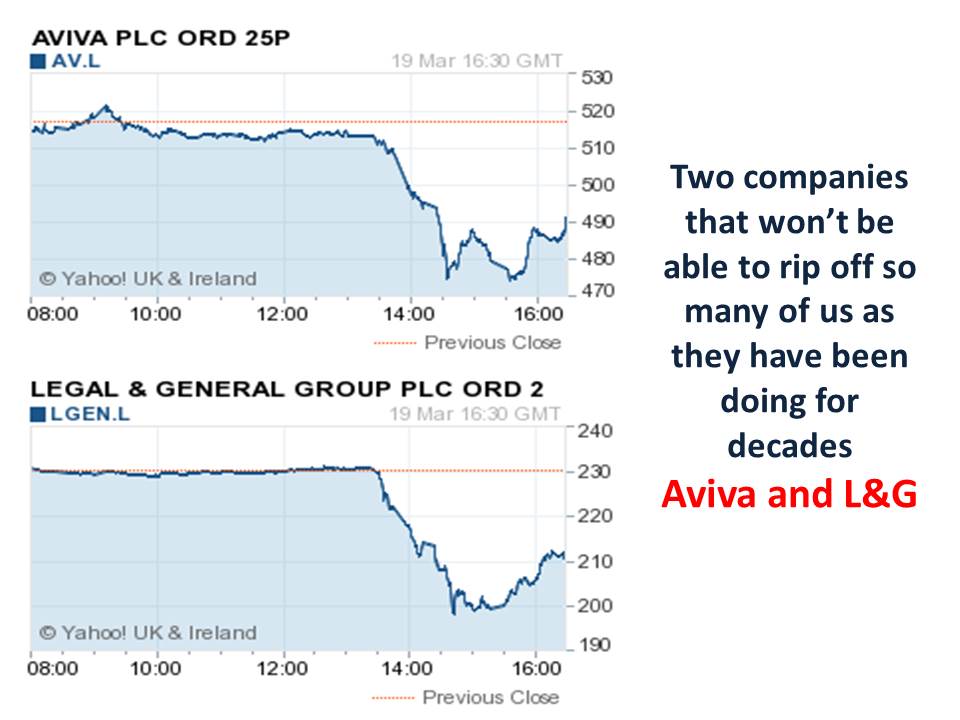
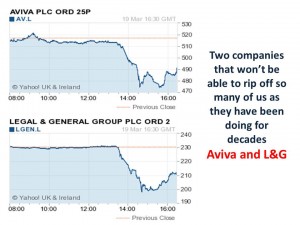
Yesterday’s budget was the usual tinkering dressed up to look like an economic policy – a penny off this, a few thousand more in tax-free savings and so on. But there was one truly revolutionary change – the reduction in the pressure for people to buy an annuity in retirement. If you want to grasp how revolutionary this was, just look at yesterday’s collapse in the share price of two companies that have been selling and mis-selling us rip-off annuities for decades – Aviva and L&G (click to see more clearly)
When you buy an annuity, you hand over your pension savings to an annuity company in return for a guaranteed level of income for the rest of your (and, if you wish, your partner’s) life. Annuity sales are falling as ever more people realise what a rip-off they are. But around 365,000 people a year are still buying annuities and at least 330,000 of them – 6,340 a week, 1,300 each working day – are getting ripped off by being sold the wrong annuity so they get many thousands of pounds less for their pension savings than they should.
If you know anyone approaching retirement, tell them to NOT, repeat NOT buy annuity. And if you know anyone who has retired and bought an annuity within the last 5-10 years, it’s probable they were mis-sold and should complain first to the annuity company and then to the financial ombudsman.
There are at least four things wrong with how annuities have been sold to us:
1. Excessive profits – The pressure to buy an annuity, of course, meant that annuity companies could get away with selling us dreadful annuity policies, which impoverished many pensioners, but made eye-wateringly excessive profits for the annuity companies
2. Not using OMO – A few years ago, after years of annuity mis-selling by the likes of Aviva and L&G, the financial regulator imposed a duty on pension companies to tell their customers that they didn’t have to buy their annuity from the company that held their pension savings. Instead they could use the Open Market Option (OMO) and buy from any annuity company to get the best rate for their particular circumstances. But while 85% of people would be better off using OMO, only around 40% do so. Thus 45% are getting fleeced due to mis-selling or due to their own ignorance or passivity
3. Not getting an enhanced annuity – There is an impressively long list of medical conditions and if you have one or more of these when you buy your annuity, you’re entitled to an “enhanced annuity”. This means you get more money than a healthier person as your annuity company expects you to pop your clogs earlier. Around 65% of annuitants are thought to be eligible for an enhanced annuity, yet only 24% get one. Again over 40% are being ripped off
4. Buying too early – About 6 months before you hit retirement age, your financial adviser or pension company will contact you to try to convince you to buy an annuity. Their sales pitch will be all about how an annuity will give you the security of an income for life:

Don’t believe it. All they want is to get your money as quickly as possible. In particular, they want to get your money before you qualify for an enhanced annuity – you may be fairly healthy at 65, but you can be sure you’ll develop some medical conditions by 70 or 75. If your financial adviser or pension company can get you to buy an annuity as early as possible, then if you do develop a medical condition or even die, tough! They’ve got your money – in fact it’s their money – and they have no need to pay you any more if you do get ill. Annuity contracts are irreversible.
In conclusion – Annuities are dreadful products. They give extremely poor value to customers while making massive commissions for salespeople and profits for annuity companies. They are often complex and usually mis-sold. And they should only be bought by a small minority of people, whereas currently around 90% of retirees are being conned into buying one.
By David Craig, on March 19th, 2014 I don’t suppose many readers had the time to watch the whole of Vladimir Putin’s speech yesterday. Being unemployed with nothing better to do, I saw the whole thing. My conclusion – Putin was wonderful. He was clear, focused, direct and devastating in the way he used withering sarcasm to expose the hypocrisy of our lying leaders.
Some of the points Putin made:
Crimea belonged to Russia – Crimea has been part of Russia for hundreds of years, apart from the brief period from 1954 to 2014.
Russia being pushed into a corner – The EU made a territory grab too far when it tried to pull the Ukraine away from Russia. Russia would not tolerate NATO tanks on its borders
Important naval base – Russia had its most important naval base in the Crimea and would not accept that base being handed over to NATO. As he said, “I would rather NATO troops came to visit us in the Crimea, than we came to visit them”
Clear referendum result – The referendum to become independent may have been rushed, but the results were so overwhelmingly in favour of independence that there could be no doubt that the Crimeans didn’t want to become part of an EU-controlled Ukraine
West’s hypocrisy over Ukrainian law – The West claims that the Crimea referendum for independence and then joining Russia broke Ukrainian law. However, when Kosovo broke Serbian law when it voted to become independent, the UN (pushed by the West) decided that the right of people to self-determination over-rode any national laws
West’s hypocrisy over international law – The West claims that Russia has broken international law by taking over the Crimea. Putin pointed out that after the West’s illegal invasions of Iraq and Afghanistan, it was good that the West finally remembered there was such a thing as international law
Nobody killed – When Putin made his speech, nobody had been killed in the Crimea, unlike the West’s disastrous military adventures in Iraq and Afghanistan
Irresponsible statements from our leaders – Given the above points, Putin (correctly in my opinion) accused our leaders of making reckless and irresponsible statements and threats that could damage international relations and economic recovery.

But perhaps the most important message we can take from the Putin speech is the contrast between when Putin speaks and when our own leaders do. With Putin you know he says what he thinks and he’ll do what he says. You can’t really say the same for puffed-up, inane, lying, self-serving, greedy, incompetent muppets like Chameleon, Clogg, Milibrain, Baroness Pig, Kerry and President O’Bummer.
(By the way, Mr Cameron, please note how rapidly a referendum can be organised if a leader really wants one)
By David Craig, on March 18th, 2014 Here he is – our great Chancellor – a man with a plan. Buffoon Osborne’s great plan is that he’s going to “build for Britain”.

For this dope, “building for Britain” means creating a new garden city on some marshland and an old quarry site just beside a river at Ebbsfleet. Here’s the site of George’s marvellous new garden city.

While I don’t like to p*ss on Osborne’s parade, I see a few possible problems. For a start, I thought the recent floods had taught us that building houses on marshland beside a river isn’t such a great idea as rising water levels after rain may mean George’s new garden city could soon resemble Venice, but with rabbit-hutch sized houses and submerged cars rather than magnificent palazzi and gondolas.
But the biggest problem is in “the numbers”. George’s garden city will apparently have 15,000 new homes. Hooray for George! An amazing 15,000 new homes! Housing crisis solved! What a genius!
But hold on a minute, if there are an average of three people in each of these homes, then that’s 45,000 people housed. Yet every month 46,000 to 50,000 new immigrants arrive in Britain. So, we actually need one of George’s wonderful garden cities to be built every 30 days – not one every 30 years – if we’re going to house all the culturally-enriching, highly productive, hard-working folk that our leaders are importing to please their EU masters and destroy Britain’s identity and heritage.
So, George isn’t “building for Britain”. He’s building for immigrants, of course using our money. But he’s not building fast enough. Remember, we need a new 15,000-home garden city every single month. Yup, a new garden city every month. Hopefully this gives some idea of the massive scale of immigration that is turning our country into a squalid, overcrowded, grey, concrete, Third-World hell-hole.
Oh, George’s great plan doesn’t look so great after all.
By David Craig, on March 17th, 2014 Today I thought I’d take a break from all the doom-and-gloom, we’re-all-about-to-die stories and write about something positive – Mind Maps. If you, your family and children and people you work with regularly use Mind Maps, then there’s no need to read any further. But if you don’t use them, then please read on.
The problem Often when given a task – making a presentation, writing an essay, doing a project, writing an article or book, organising a meeting or conference, developing a plan, dreaming up a new marketing approach, producing a sales brochure – many people struggle to find sufficient things to talk/write about. This is partly because we think in a linear fashion. So, we’ll jot down a few ideas then start to dry up.
The solution – Mind Maps These help us break our pattern of linear thinking and generate a huge number of ideas in just 5 to 10 minutes. I tend to use them when planning a book or when preparing a talk. They’re particularly effective for school children and students. If some of your brood are ever agonising over what to write for an essay or your team at work are having difficulty with some task or other – help them do a Mind Map and you’ll usually be surprised at how quickly the Mind Map sets their thoughts free. I wish I’d been taught how to do Mind Maps when I was at school and university.
How to do a Mind Map They’re very simple. You just write the subject of the task in the centre of a piece of paper or flip chart then start drawing branches as ideas occur to you. Then each branch will tend to lead to other sub-branches and these will in their turn lead to sub-sub-branches and so on. Here’s an example I found on Google (click to see more clearly)

So, if was giving a talk about say “Money”, I’d write “Money” in the centre of the page then some of my primary branches would be things like banks, savings, pensions, annuities etc. Each of these would lead to sub-branches, for example “pensions” might lead to SIPPs, charges, state pension, retirement etc. And each of these would lead to sub-sub-branches.
And here’s a Mind Map looking at the possible uses of Mind Maps (click to see more clearly)

By David Craig, on March 16th, 2014 It seems as if every few months, some official body or some left-wing supposed think tank issues a report claiming immigration has been a huge benefit for the British economy. The most recent one was from the (IMHO) biased sycophant Robert Chote’s ludicrous £2m a year Office of Budget Responsibility. So, if you’ll bear with me, I’ve done my own back-of-a-fag-packet calculation of the “economic benefits” of our masters’ attempts to drown us with immigrants as they hand over control of our country to their corrupt, wasteful, unelected bosses in Brussels.
About 532,000 people come to the UK each year. Of these, around 209,000 are from the EU and 323,000 are non-EU.
If we take the 209,000 from the EU. About 20% will be unemployed and will cost us about £11,800 each in benefits and public services (just health, education and policing). That’s 41,800 people costing us £493m a year. Of the remaining 167,200, probably around 146,900 (70% of the total) will be doing jobs where they don’t earn enough to pay much in tax, but will be costing about £1,800 each in services – total cost £264m. Another 10,450 (5%) will be paying about as much in tax as they take in services. And 10,450 will be paying say £5,000 a year each more in taxes than they take in services – £52m contribution. Moreover, those 167,200 working will be forcing at least 33,440 Brits onto the dole, costing us another £500m in benefits and services.
So the total cost of each year’s immigration from the EU is around £1.2bn (click on chart to see more clearly)

As for the 323,000 non-EU immigrants. About 30% (96,900) will be unemployed costing us about £1.5bn a year in benefits and services. Of the remaining 70% (226,100) about 193,800 (60% of the total) will not be earning enough to pay much tax but will be taking about £1.05bn in services. About 16,150 (5%) will be cost neutral as they’ll be paying as much in tax as they take in services, while the remaining 16,150 may be contributing about £81m more in tax than they take in services. And, of course, the 226,100 working will displace about 45,220 Brits from jobs costing us around £678m.
This brings the cost of non-EU immigrants to £3.1bn a year (click to see chart more clearly)

So, the total cost of just one year’s immigration must be in the region of £4.3bn. As this tsunami of immigration has been going on for more than 10 years, we’re now paying over £43bn a year for immigrants – a figure that will increase by about £4.3bn a year as the uncontrolled floods of immigrants keep pouring into the country.
And this calculation doesn’t take account of the social costs of seven million new arrivals – crowded hospitals, collapsing health services, increases in crime, schools where most of the children don’t speak English, rising housing prices, overcrowding and so on.
Anyone who claims immigration has been good for Britain is either a liar or a fool or, more usually, both.
(btw if you want to show your support for this website by buying a copy of GREED UNLIMITED, then hurry while stocks last!)
By David Craig, on March 15th, 2014 Below are pictures of two obviously extremely courageous men. One is Malaysia’s Chief of the Armed Forces General Tan Sri Zulkifeli bin Mohd. Zin and the other is Sacha Baron Cohen as General Aladeen, ruler of the Republic of Wadiya, from Baron Cohen’s film “The Dictator”.

There is one striking similarity between these two great warriors – the impressive array of medals adorning their manly chests. I think we know how General Aladeen got his medals. As for Malaysia’s Chief of Armed Forces General Tan Sri Zulkifeli bin Mohd. Zin – I’m not sure what all his medals and ribbons are for, but I guess that plane spotting wasn’t one of them.
Have a good weekend.
By David Craig, on March 14th, 2014 As we move towards yet another Osbornomic budget, all the usual idiots are blethering on about how we need tax cuts. After all, these buffoons argue, with the economy growing, our great chancellor can afford to give us back a bit of our money. What planet are these utter twats living on???
Yesterday, I hopefully showed that the only way our masters could make it look like the economy was growing was by fiddling the inflation figures. Today, I’ll try to show how “healthy” our national finances are.
1. Government spending – is still totally out of control and is still heading remorselessly upwards. It was £672.3bn when the Coalition took over in 2010, it will be £728.7bn in 2015. (I know there seems to be a drop in 2013, but suspect when all the figures are in, 2013 will go a bit higher) (click on charts to see more clearly)

2. Government debt in £trn – this is also shooting ever upwards in spite of the supposed “economic growth” which I believe doesn’t exist

3. Government debt per capita – this is also climbing towards the skies

I’m not an economist. And I realise that there are many very clever economists running the country, writing in the press and appearing in the media. But when I look at the above 3 charts, I fail to see the bright lights of economic recovery that everyone else is celebrating. I apologise for being really really stupid.
By David Craig, on March 13th, 2014 We hear it every almost every day – “the UK economy is growing”, “we’re out of recession”, “the worst is over”, “there’s light at the end of the tunnel”, “UK economy is fastest growing in Europe”, “UK growing faster than Germany” etc etc. And sure enough, if you look at the basic numbers, this seems to be true (click to see charts more clearly)
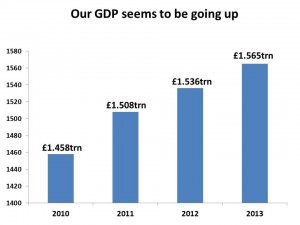
But these figures don’t take account of inflation. And once you throw in inflation, as far as I can see, the UK economy grew in real terms by £16bn in 2010 and then shrank in real terms by £18bn in 2011, £15bn in 2012 and £9bn in 2013
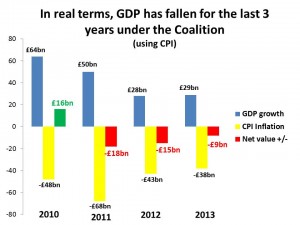
And I’m just using CPI as a measure of inflation. Had I used RPI, things would look a fair bit worse.
(Many of you will be a lot smarter than me and you might look up the official Government ONS inflation-adjusted GDP figures. If you do, you’ll find the economy grew each year and didn’t shrink as I suggest in the above chart. But the Government and ONS don’t use either CPI or RPI when adjusting GDP for inflation. They use their own special measure called the “GDP deflator”. This is usually much less than CPI and a country mile less than RPI. For example, in 2010/11 when CPI was at about 4.5% and RPI probably over 5%, the Government’s wonderful GDP deflator was only at 2.8%. By using the GDP deflator, our masters can make decline look like growth. Yet we hear not a peep of protest from the (IMHO) sycophantically, self-serving Robert Chote, boss of the £2m a year, laughably titled “Office for Budget Responsibility“)
If I’m right, this is far from good. But there’s worse to come. The supposed growth the politicians and economists blether about has been bought at enormous cost. We borrowed £140bn in 2010, £150bn in 2011, £130bn in 2012 and £120bn in 2013. That’s £540bn that will have to be paid back at some point. Again, one would expect a genuinely “independent” Office for Budget Responsibility to be howling in protest against this appalling level of economic mismanagement. Sorry, I can’t hear you Robert Chote.
So, taking account of CPI inflation and government borrowing, does this mean the Coalition is effectively destroying massive amounts of value every year?
I don’t know. But I do understand that the faster we supposedly crawl out of recession, the deeper we sink into a cesspit of debt. And that just doesn’t look (or smell) like something we should be celebrating.
By David Craig, on March 12th, 2014 (I’ll deal with the myth of our economic growth tomorrow)
I’ve written before about why I think the state pension will eventually be abolished https://www.snouts-in-the-trough.com/archives/8608 Last night I found out how this will happen.
I attended a meeting held by a think tank called Policy Exchange. The subject was how to get more ordinary people to save more for their pensions. There were two kinds of attendees:
Firstly, some public-sector big bosses and middle-ranking bureaucrats from the Bank of England, the DWP and the financial regulators. The great Lord Turner, formerly boss of the totally ineffectual and probably institutionally corrupt and now abolished Financial Services Authority, was one of the speakers as was Tory MP and former Minister of State for Work and Pensions Mark Hoban. Note that all these people would have extremely generous final-salary, inflation-protected pensions (paid for by us) as well as a delightfully early retirement age.
The other group were people from pension fund managers eager to encourage the Government to make us save more as that meant more money for them in management fees.
The general theme of the meeting was that we ordinary people were not saving enough and had to be pushed or even coerced into saving more as our pensions were unaffordable. Moreover, too many of us were living too long and our care costs were becoming an intolerable burden on the state. Their own hugely generous, taxpayer-funded pensions and early retirement were, of course, completely affordable and well deserved after the huge contribution they had all made to our country.
The majority there felt that we should fully adopt the Australian model. There it’s compulsory for everyone to save 10% of their salary into a superannuation fund and (if I understand correctly) very few people get the Australian state pension as they are considered to have sufficient savings to provide for themselves. However, the great and the good (and of course well-pensioned) at the meeting realised that they couldn’t immediately force us plebs to save for our pension as we might realise that pension savings were just another tax in addition to income tax and NI. So, they planned to do what they called the “art of the possible” – move to compulsory pension saving in steps.
Step 1 – Introduce auto-enrolment for the Workplace Pension. This is already happening with 2.9 million workers in larger companies already signed up and millions more in smaller companies set to join over the next couple of years all paying about 8% (including employer contributions and tax rebates)
Step 2 – Once people get used to paying into a pension, move the goal posts – make paying about 6% compulsory and then auto-enrolling us to pay another 4% to 6% ” voluntarily” because the 8% of the current Workplace Pension was not sufficient to provide most people’s pensions
Step 3 – Cut the link between years of NI contributions and entitlement to the state pension, so that the state pension became a “benefit” (like unemployment benefit) rather than an “entitlement” based on years of NI contributions
Step 4 – Now that the state pension was a benefit, not an entitlement, only those with little to no pension savings would get the state pension
In the meantime, our masters would keep on increasing the age at which the state pension would be paid to us, while preserving their own early retirement opportunities.
This move towards compulsory saving and abolition of the state pension for all but the very poor will happen over several years – maybe 15 to 20. But it will happen as the state pension is unaffordable.
This means that, for anyone earning less than say £20,000, every pound they save into a pension scheme will result in reducing their eligibility for the state pension. They are being suckered.
Oh, and there was one other conclusion from the meeting – that setting a cap on the fees pension fund managers can charge us would “restrict financial innovation“. This was enthusiastically endorsed by the attendees from pension fund management companies like Schroders.
Are we being scammed? Yes we are!
(Sadly not a single person bought a copy of GREED UNLIMITED yesterday, so I’m not going to reach my absurdly low target of selling just one copy a day. Though my thanks to the reader who offered to buy his 3rd copy if it helped me fund the costs of running this website. But there’s no need to go that far. It’s not the money that’s important, it’s just my hurt pride that I wrote what I thought was a reasonable book and hardly anyone wanted to buy a copy)
|
|