|
|
By  David Craig, on April 4th, 2013 A group of shareholders are suing RBS directors (including Fred Goodwin and Sir Tom McKIllop) and the bank for compensation for money they lost when they invested in RBS’s £12bn rights issue in 2008. The investors claim that directors wrongfully told them the bank was financially sound. Just 6 months after the rights issue, RBS became Britain’s largest bankruptcy and was rescued by a £45.5bn taxpayer-funded bail-out.
Fred Goodwin first came to my attention in 2005. Just after I published RIP-OFF The scandalous inside story of the consulting money machine, I was contacted by someone who had worked with Fred Goodwin at Deloittes on the BCCI (Bank of Credit and Commerce International) bankruptcy. This person alleged that the team led by Fred Goodwin had defrauded BCCI creditors of around £50m. The person also gave me details of how Goodwin and Deloittes allegedly carried out the fraud.
I reported this to the SFO and to the Bank of England. I even had a phone conversation with a very senior figure at the BoE during which I suggested that Goodwin was not a fit person to run a bank. But this was at a time when Blair and Brown were sucking up to bankers – they gave honours to 23 bankers several of whom ruined the banks they were running – so no action was taken.
The claim against Goodwin. McKillop and others centres around the prospectus issued in connection with the 2008 £12bn rights issue. I haven’t read the prospectus, but while writing FLEECED How we’ve been betrayed by politicians, bureaucrats and bankers I did look at the statements made by the at that time Sir Fred and Sir Tom in their last financial report just before the bank they were supposed to be running dramatically went tits up.
Fred Goodwin was Forbes Magazine Businessman of the Year in 2002. In early 2008, Fred was able to announce record results for 2007: ‘For the Royal Bank of Scotland Group, 2007 was defined by another strong operating performance and by the acquisition of ABN Amro’. Fred helpfully explained to the world at large why his bank was so successful: ‘Delivering such a robust financial performance in this environment is the consequence of action in two areas: over a number of years we have diversified the Group’s income streams and last year also saw us benefit from our focus on credit quality and risk management’.
Some of us might be tempted to wonder whether Fred’s claim of ‘focus on credit quality and risk management’ might not constitute a crime for gross misuse and abuse of the English language. It might even be construed as misleading shareholders and therefore worthy of prosecution.
Just before the bank’s ignominious collapse, Fred’s chairman, the £750,000 a year former pharmaceuticals boss Sir Tom McKillop also seemed proud of the bank’s diversification strategy and admirable credit control: ‘We have witnessed the benefits of the Group’s long-standing focus on credit quality and the diversification of our income streams which have allowed us to deliver record profits’.
IMHO the statements made by Goodwin and McKillop, shortly before the bank collapsed, are intended to mislead shareholders and I hope that the bank’s shareholders grind these two (IMHO) “greedy, lying fraudsters” into the dust.
By David Craig, on April 3rd, 2013 In the coming financial year which begins this Friday 5 April, our useless government will increase the budget of the Department for International Development (DfID) from £7.9bn to £10.5bn. This is a pretty impressive rise of £2.6bn (up 33%) at a time when 40,000 are being sacked from our armed forces and when police numbers are being cut by 32,400. Coincidentally, just this £2.6bn increase in foreign aid is enough to comfortably pay for the 72,400 police and military who are losing their jobs.
Our hopeless government claims that foreign aid works and that by 2015, British money will have helped to vaccinate 55 million children against killer diseases and put 9 million through primary school. But repeated studies by the UN have shown that somewhere between 80% and 90% of all money given to foreign aid projects is lost either through incompetence or corruption. For example, about a year ago the South African government set aside over £2m to buy books for schools. Not a single book was bought, but the money disappeared.
One of the countries to benefit from our government’s generosity with our money is that earthly paradise Pakistan – one of the most corrupt countries in the world. Pakistan gets about £450m a year much of which supposedly goes on providing education to the poor. Pakistan’s president is known “affectionately” to his people as “Mr Ten Per Cent”. That might provide a clue as to his honesty.
But does Pakistan really need our money? Over 54% of all the money spent by Pakistan’s government goes on the military and on servicing the country’s debts, while less than 2% goes on education. Moreover, out of Pakistan’s 180 million population, less than one million (860,000) pay any income tax. According to an article in the Telegraph today, 35 out of 55 Pakistani cabinet ministers paid no income tax at all. Similarly 251 out of 341 members of the National Assembly chose not to pay any income tax either.
We’re paying for Pakistan’s schools so its rich don’t have to pay any tax and so that the country can squander the money it does have.
In fact, we can see the same pattern in most other countries we give aid to. Either the aid is stolen or else we pay for things like vaccinations and schools and water supply so that the politicians and bureaucrats can spend what little money their countries do have on their own luxury homes or else send it to their offshore bank accounts – ten times as much money leaves Africa for offshore bank accounts as the whole world gives Africa in aid each year.
This leaves us with a terrible dilemma. If we reduced or even stopped aid, millions would suffer because the rulers of most of the countries to which we give aid are so venal that they would rather steal their countries’ money than use it for the welfare of their people. But if we carry on giving aid, we allow these countries’ leaders to continue with their grand larceny.
By David Craig, on April 2nd, 2013 I’m not a religious person. But I have to admit that it seems that a miracle has happened in Britain – 500,000 of the sick, the lame and the handicapped have suddenly been cured.
About 20 years ago, there were 1.1 million people claiming Disability Living Allowance. By 2012 this had almost trebled to 3.2 million people. This huge increase in the number of “disabled” people meant that Britain was paying about £13bn a year in Disability Living Allowance – about twice as much per head of population as countries like France and Germany.
As the Government has gradually tightened up the checks on whether Britain’s 3.2 million “disabled” are actually disabled, a great miracle has happened. At least 500,000 “disabled” have been miraculously cured and have decided not to claim Disability Living Allowance anymore rather than having to face a medical check to see if they are actually disabled. This is truly amazing. Either it’s a miracle that so many people have been cured or else many of Britain’s “disabled” were actually just lazy, greedy, feckless benefits scroungers.
Of course, with hundreds of thousands being checked, there will be cases when people who really are disabled are declared fit to work by some overzealous bureaucrat or just due to bureaucratic bungling. And these cases, will be eagerly seized upon by the Guardian and the BBC to prove that the government is taking money from the poor to give to millionaires. But bleating from the Guardian and the BBC should not be allowed to cover up the fact that for at least one million healthy people, Disability Living Allowance is just a way for them to scam money off British taxpayers.
(If a few readers of this blog were to buy copies of my latest book GREED UNLIMITED to help me pay the costs of running this website, that would be gratefully appreciated)
By David Craig, on April 1st, 2013 Sorry, but today my post is a bit long. But that’s because the issue I deal with is quite serious.
Yesterday I exposed the horrific exposure of UK banks to the debt of European countries. Some of this money was loaned to countries that are financially stable, but a lot has been loaned to countries that are virtually bankrupt. Some of the “good debt” includes $328bn to Germany and $198bn to Holland. Some of the more dodgy loans include $242bn to socialist France, $137bn to almost bankrupt Ireland, $85bn to bankrupt Spain, $57bn to bankrupt Italy, though fortunately only $8bn to thoroughly bankrupt Greece.
So what happens if just one of these countries gets into trouble and debt-holders are forced to take a “haircut” of say 20% or 30%? Well, that would probably bankrupt a couple of UK banks. But this time, our Government is drowning in debt and so can’t afford to hand out tens of billions of taxpayers’ money to save its banker friends.
Question – where else could the Government find the money to yet again bail out bankrupt UK banks? Answer, by “doing a Cyprus” – by handing over some of the £550bn of our savings to the banks in return for some, probably largely worthless, shares in the bank we are saving from its overpaid over-bonused bosses’ greed and incompetence.
But surely no British government would dare confiscate our savings and hand them over to banksters? After all, aren’t the first £85,000 of our savings guaranteed? Unfortunately, I have bad news for you
A joint paper from the US Federal Deposit Insurance Corporation (FDIC) and the Bank of England (BoE) dated December 10, 2012, shows that these plans have been long in the making; that they originated with the G20 Financial Stability Board in Basel, Switzerland; and that in future major bank bailouts will not be paid for by taxpayers but by shareholders and creditors.
Most people probably think that when they deposit money in a bank, they still own that money. Wrong. When you put money in a bank, you are lending money to that bank in return for, you hope, some interest. This means the money belongs to the bank and you are one of the bank’s creditors.
The 15-page FDIC-BOE document is called “Resolving Globally Active, Systemically Important, Financial Institutions.” It explains that the 2008 banking crisis has made it clear that some other way besides taxpayer bailouts is needed to maintain “financial stability.”
The key points of the report are probably:
1. Future bank bailouts will be funded by shareholders and creditors (including depositors)
2. In the case of a major bank failure, depositors (savers) will be “bailed in” and will either lose part (or all) of their money or else part (or all) of their money will be converted to banks shares in the failed bank
3. A EU directive – the EU Recovery and Resolution Directive – allows insured deposits to be bailed in. In layman’s terms, this means that deposits up to £85,000 in the UK and up to €100,000 in the Eurozone can be used to cover the failed bank’s losses
You have been warned. This is NOT an April fool’s joke. Repeat, this is NOT an April fool’s joke.
(Incidentally, the Australian government recently passed a law reducing from 7 years to 3 years the time that a bank account there could be dormant before the contents of that supposedly “dormant” account could be moved from the bank to the Australian government. All around the world, governments are realising that there are rich pickings to be had in bank deposits. This is NOT an April fool’s joke)
By David Craig, on March 31st, 2013 The chart below shows the exposure of banks in a few key European countries to the debts of other countries (in $bn).
You should read the chart like one of those old-fashioned tables of distances between towns that we used to use before we all got satnavs. Here you should work vertically, then horizontally. So, for example, Germany’s banks are exposed to $460bn of UK debt, while British banks are exposed to $328bn of German debt.
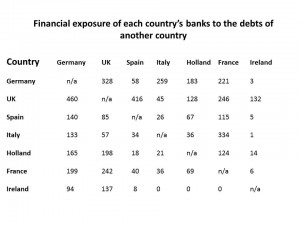 Similarly, French banks are exposed to $115bn of Spanish debt, while Spanish banks are exposed to $40bn of French debt. And UK banks are exposed to $198bn of Dutch debt while Holland’s banks are exposed to $128bn of UK debt. And, ludicrously, bankrupt Spain’s banks are exposed to $34bn of bankrupt Italy’s debts, while bankrupt Italy’s banks are exposed to $26bn of bankrupt Spain’s debt.
So what does this all mean? It means that the slightest wobble in any major European country will bring the whole of Europe’s banking system tumbling down with such a mighty crash that it will be heard from outer space. This is why the EU cannot allow any country to default or any major bank to implode. This interconnectedness of debt between many mostly bankrupt countries could lead one to describe the whole European economy as a “house of cards in the face of a hurricane”. But, a house of cards in the face of a hurricane actually appears quite solid compared to the European countries’ dependence on each other not defaulting.
This is the first time these figures have ever been revealed in such a horrifyingly simple format – aaaaaarrrrrrgggggghhhhhhhhhh!
Still, at least the Aussies can laugh at Europe’s debt house of cards: “How can broke economies lend money to other broke economies who haven’t got any money because they can’t pay back the money the broke economy lent to the other broke economy and shouldn’t have lent to them in the first place because the broke economy can’t pay it back?” Enjoy https://www.youtube.com/watch?v=I5QwKEwo4Bc&feature=relmfu
(Btw I’d be grateful for your support for this website if you would buy some copies of my latest book GREED UNLIMITED)
By David Craig, on March 30th, 2013 It’s not much fun being a Cassandra – making dismal prophecies that nobody believes. But our ruling elites (politicians, journalists, bureaucrats and bankers) are so incompetent, self-serving and dishonest that someone has to try to tell the truth.
When I wrote PLUNDERING THE PUBLIC SECTOR I attacked New Labour for wasting £70bn of our money on consultants. In particular, I lambasted the £10bn NHS IT project and predicted it would end in utter failure. At the time, I was summoned to a meeting with Sir John Bourne (then head of the National Audit Office – NAO) and told in no uncertain terms that an NAO report had found that the NHS IT project was well-managed and would be a success. Seven years and over £2bn later the whole mess was abandoned.
In SQUANDERED, I predicted that Gordon Brown would waste over £1trn of our money. This was at a time when the sycophantic press were still telling us that Brown was an economic genius whose prudence was legendary. Few people believed me. But now we know that Brown was financially incontinent, a recidivist liar and probably the worst chancellor Britain has ever been cursed with.
In my blog, I used the fact that there are over a million Romanians and Bulgarians in Italy and a similar number in Spain, to predict that well over a million will come to Britain. Our politicians are talking about just 50,000 a year. In a few years, we’ll see who was right.
And now I cannot come to any other conclusion other than that Britain is going to face a massive financial crisis somewhere around 2017. The problem is, of course, our ever-rising debt – £700bn in 2010, £1.15trn now, £1.4trn in 2015, £1.52trn in 2016, £1.64trn (120% of GDP) in 2017 and so on. We cannot go on like this. It has to end in tears.
 Our debt as a % of GDP (vertical axis) is almost as high as Portugal, Ireland and Belgium. But more worryingly, only 3 countries – Spain, Ireland and Greece – have a higher deficit (horizontal axis). The deficit, of course, is the rate at which our debt increases.
Our politicians and newspapers are keen to tell us all about the problems in the Eurozone, particularly in Greece, Spain, Italy and Cyprus. But by the time of the 2015 election, Britain will be in a worse financial state than some of the most bankrupt Eurozone countries.
What will happen? We can’t go on printing electronic money to buy our own debt. So at some point markets will lose confidence in the British government, the interest we pay on our debt will shoot up to £80bn or more a year and our government will be forced by rising interest costs or by the IMF to take drastic action. As Labour will be in power, there won’t be any serious cuts to benefits or the NHS. So there’s only one thing the Labour government can do to raise money – punitive taxes on our earnings, savings and pensions and capital controls to prevent us moving our money abroad – similar to what we’ve seen in Cyprus.
Think this can’t happen in Britain? Well, the Bank of England issued a report in December 2012 where it recommended confiscation of savings, even below the supposedly guaranteed £85,000 in the event of a major bank collapse https://www.economicsfortherestofus1.blogspot.ca/2013/03/the-usa-uk-and-eu-are-planning-to-take.html
By David Craig, on March 29th, 2013 Here’s a photo of a polar bear apparently stranded on a tiny ice floe due to man-made global warming melting Arctic ice:

This is the kind of photo ecofascists tend to use to warn us about the destructive results of their supposed “man-made global warming”.
And here’s a table showing the frightening decline in polar bear numbers due to man-made global warming. Whoops, sorry. Polar bears are thriving. Their population has shot up from somewhere around 5,000 in the 1950s to above 25,000 by 2005. Some experts even think there may now be 32,000 polar bears

And here are 10 reasons not to worry about the survival of polar bears.
https://polarbearscience.com/2013/02/26/ten-good-reasons-not-to-worry-about-polar-bears/
In fact, the most drastic declines in polar bear numbers have been due, not to melting ice, but during periods when there was too much ice preventing them reaching their main food source – seals. And some experts believe the biggest threat to polar bears now is that there are too many all competing for the same food resources.
If the ever-increasing number of polar bears knew that all the handwringing, bleeding heart, misguided ecofascist greenies were predicting their imminent disappearance, I imagine they’d be rather surprised.
By David Craig, on March 28th, 2013 Here we go again. A spell of cold weather and our mostly foreign-owned energy companies slam up their prices claiming they are having to pay more for their gas supplies. Lies, lies, lies, lies.
Here are just a few real facts and figures:
1. Our often foreign-owned energy companies make four to five times as much profit in the UK than they are allowed to make in their properly regulated home markets.
2. They are so profitable in the UK that Scottish Power’s Spanish owner Iberdrola recently lent its American subsidiary £800m leeched from its UK customers, as the American subsidiary needed the money to meet investment commitments it had made to US regulators
3. Last year SSE (formerly Scottish and Southern Energy), Britain’s second biggest energy firm, saw its profits increase by 32%. Meanwhile SSE’s eight million customers saw their fuel bills rocket by 9% (well above the rise in inflation), adding £119 to the average yearly bill. All the other energy companies reported increased profits last year of between 25% and 35%.
4. Since 2006-7, the useless UK regulator Ofgem’s budget increased from £18.6m to £32.6m and yet due to Ofgem’s pathetic efforts, the UK is one of the most profitable energy markets in the world. Ofgem has estimated that energy companies will triple their profits this year but does nothing to protect consumers from predatory pricing.
5. As you’ll see in the diagram below (I apologise that I have used this before), our energy companies claim they only increase prices when wholesale prices rise, but actually keep pushing up prices whether the wholesale prices they pay rise or fall.

Btw it would be gratefully appreciated if just a few people would buy some copies of my latest book GREED UNLIMITED. I feel it would be a shame to have to pulp the remaining copies
By David Craig, on March 27th, 2013 The Tories refuse to tell us how many Romanians and Bulgarians are likely to move to bankrupt Britain. Meanwhile Labour and its official media arm, the BBC, bleat on about how immigration has “increased Britain’s cultural diversity”. So maybe I can help give some facts and figures.
Spain and Italy have not had restrictions on Romanians and Bulgarians. So let’s see what has happened there. Currently there are about 920,000 Romanians and 170,000 Bulgarians in Spain. In Italy there are about 997,000 Romanians and over 70,000 Bulgarians. Britain has much more generous benefits and more jobs than Spain or Italy, So the absolute minimum number that will be moving here will be well over one million. Probably it will be closer to two million.
Now, let’s look at some other figures. Unemployment amongst Romanians and Bulgarians in Spain is 36.4% – that’s about 396,760 immigrants who are unemployed. So we can expect somewhere in the region of 400,000 Romanians and Bulgarians to be claiming benefits for housing, council tax and unemployment here in Britain.
Let’s look at more figures: Romania and Bulgaria are miserable dumps run by mafias not real governments. A worker in either country will probably only earn about £175-£200 per month. So what happens if a Bulgarian or Romanian moves to Britain?
The Department for Work and Pensions says the average claimant (across all nationalities) receives £390 a month in housing benefits and £65 a month in council tax benefits. They can also claim £88 a month for their first child and £58 a month for any child after that. Then there’s about £300 a month unemployment benefit. It means someone with three children could collect £960 a month in benefits. So a family with three children will get in benefits in Britain about five times what they can earn working in their own countries. If they have five or six children, they’ll be pocketing what for them would seem a fortune. So you have to ask the question – why would any of the 29 million Romanians and Bulgarians remain in their own countries, when they can live what will seem to them a life of luxury here?
Of course, not all the people will leave Romania and Bulgaria. Those with good jobs and houses will stay. But for the poor, the unemployed, gypsies, the workshy, the feckless, the criminal and the low-skilled, they would be completely crazy to stay.
Let’s be clear – we have handed over control of our borders and our benefits system to Brussels. There is nothing we can do to prevent the inevitable arrival of well over a million Romanians and Bulgarians. And there is nothing we can do to deny them access to benefits, schooling, healthcare and housing as that would be “discrimination”.
Our politicians spout garbage to cover over their own impotence. I’ve tried to give you the facts and figures. The arrival of over a million (probably two million) mostly low-skilled, poorly-educated people is going to have a catastrophic effect on our education system, the NHS, housing and our economy and will cost us at least £30bn a year (£1,000 from every taxpayer). That’s £30bn we don’t have. This is the truth the politicians and the BBC are afraid to tell us.
By David Craig, on March 26th, 2013 Hopefully most people have realised that virtually every time our politicians move their lips, they lie to us. This has especially been true with immigration.
Around 2000/1 Blair came under pressure over the rising number of asylum seekers. So he promised to take action. The chart shows the result.

Blair reduced the number of asylum seekers – but only by throwing British citizenships (and British passports at them) to hide the problem rather than solving it. And now David Liar Cameron is talking tough on immigration. But. of course, it’s all verbal flatulence and nothing will change because we’ve handed over control of our borders and our benefits system to the EU
In theory, to get British citizenship you must have spent at least 3 years in Britain and either have studied English for one year or else passed the “Life in the UK” test. Although it’s multiple choice, this test is far from easy. Here are sample questions: “What is the role of the National Trust?” “How often are you required to take your vehicle for an MOT if it is over 3 years old?” “What must a candidate have in order to become a local councillor?” “What are National Insurance contributions used for?”
So I would like to thank one of the readers of this blog for telling me what really happens at citizenship ceremonies:
“I have witnessed many citizenship ceremonies in an area of ********. Here are some observations.
1 At least 30% – possibly more do not speak English as is a requirement
2 Less than 2% can’t attend on the set day because they are working. Those working usually pay for a private ceremony to fit in with their work commitments. In this area we take 1 public ceremony with a maximum of 30 attendees – the majority do not have a problem attending because they don’t work.
3 There have been instances of women taking citizenship in a full burkha and reluctant to be identified
4 There are a number of ‘bodies’ that act as intermediaries for new applicants, for a fee. It cannot be coincidence that these citizens are the ones with limited knowledge of English language.
5 Less than half sing the national anthem (but how would they if they can’t speak English?)
6 There is no requirement for a new applicant to have worked or contributed to our society
In short – for a few hundred pounds – a new citizen not only gains a British passport but access to many hundreds thousands of pounds in benefits, education and healthcare – not to mention the state pension which is slowly being moved out of reach for the natives of UK who have worked all their lives.
Citizenship needs exposing for the gravy train that it is”
So, please don’t believe a word recidivist liar Cameron says
|
|